







IDLC Finance PLC, one of Bangladesh’s leading non-bank financial institutions, reported a standalone net profit of BDT 1,419.2 million for the first nine months (9M) of 2026, marking a 4.0% year-on-year increase from BDT 1,364.6 million in the same period of 2025. The earnings growth was driven by a 40.0% jump in investment income, mainly from government bonds, which more than offset a 10.3% decline in net interest income and higher tax and provision charges.
Loan Book Shrinks 1.3% Since December to BDT 120,453.0 Million
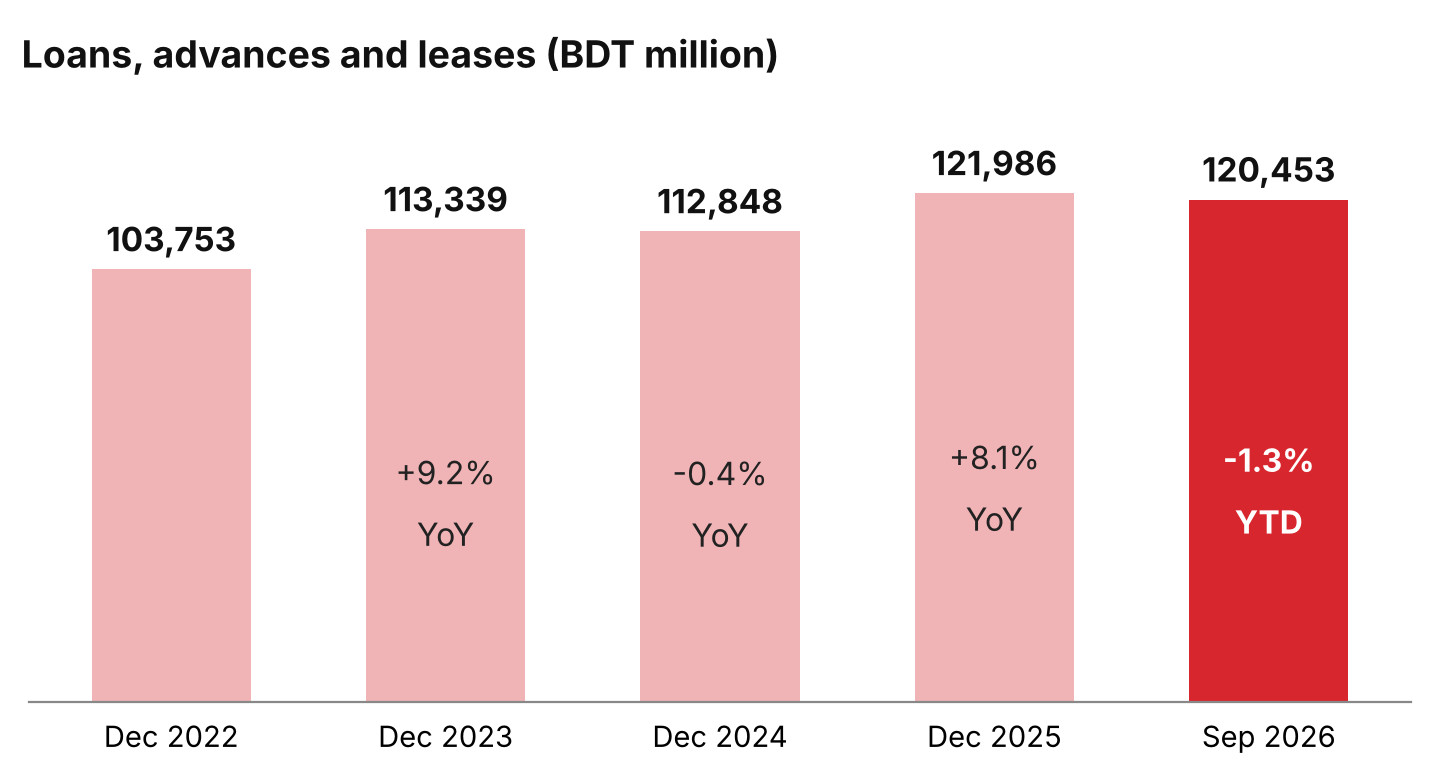
IDLC Finance’s loans, advances and leases stood at BDT 120,453.0 million as at 30 September 2026, down 1.3% from BDT 121,985.6 million at the end of December 2025, a decline of BDT 1,532.6 million in nine months. Compared with September 2025, the loan book was down 1.0%. On a year-end basis, loans grew 9.2% in 2023, slipped 0.4% in 2024 and recovered 8.1% in 2025, indicating that credit growth has stayed uneven over the review period.
NPL Ratio Eases to 4.09% as Bad/Loss Loans Fall 23.7%
IDLC Finance’s total non-performing loans (NPLs), comprising sub-standard, doubtful and bad/loss loans, stood at BDT 4,928.0 million as at 30 September 2026, down 8.8% from BDT 5,405.6 million at the end of December 2025. As a result, the NPL ratio improved to 4.09% from 4.43%. On a year-end basis, the ratio had risen from 3.81% in December 2022 to 4.46% in December 2023 and stayed broadly flat at 4.45% in December 2024 and 4.43% in December 2025.
Classification | Dec 2022 | Dec 2023 | Dec 2024 | Dec 2025 | Sep 2026 | YTD Growth |
|---|---|---|---|---|---|---|
Sub-standard | 1,244.2 | 990.8 | 656.7 | 882.4 | 1,067.6 | 21.0% |
Doubtful | 730.2 | 709.5 | 707.5 | 688.4 | 932.7 | 35.5% |
Bad/Loss | 1,977.9 | 3,358.4 | 3,658.6 | 3,834.8 | 2,927.7 | -23.7% |
Total NPL | 3,952.2 | 5,058.7 | 5,022.8 | 5,405.6 | 4,928.0 | -8.8% |
NPL ratio | 3.81% | 4.46% | 4.45% | 4.43% | 4.09% | – |
Source: IDLC Finance PLC standalone financial statements. Year-end balances as at 31 December and latest as at 30 September 2026, in BDT million. YTD growth = Sep 2026 vs Dec 2025.
The fall in NPLs came entirely from the bad/loss category, which dropped 23.7% to BDT 2,927.7 million from December 2025, reducing its share of total NPLs to 59.4% from 70.9% at the end of 2025. This was largely a result of write-offs: the company wrote off BDT 1,649.6 million of loans against provisions during 9M 2026, compared with BDT 308.8 million in the whole of 2025. Recovery from previously written-off loans rose 24.0% to BDT 77.6 million.
However, the early-stage categories point to fresh stress. Sub-standard loans rose 21.0% to BDT 1,067.6 million and doubtful loans increased 35.5% to BDT 932.7 million since December 2025. Together, these two categories now account for 40.6% of total NPLs, up from 29.1% at the end of 2025. Loans in the special mention account (SMA), the watch-list stage before classification, also more than doubled (up 139.3%) to BDT 4,375.3 million, while the interest suspense account rose 65.0% to BDT 1,550.7 million.
Deposits Rise 5.3% to BDT 116,934.3 Million
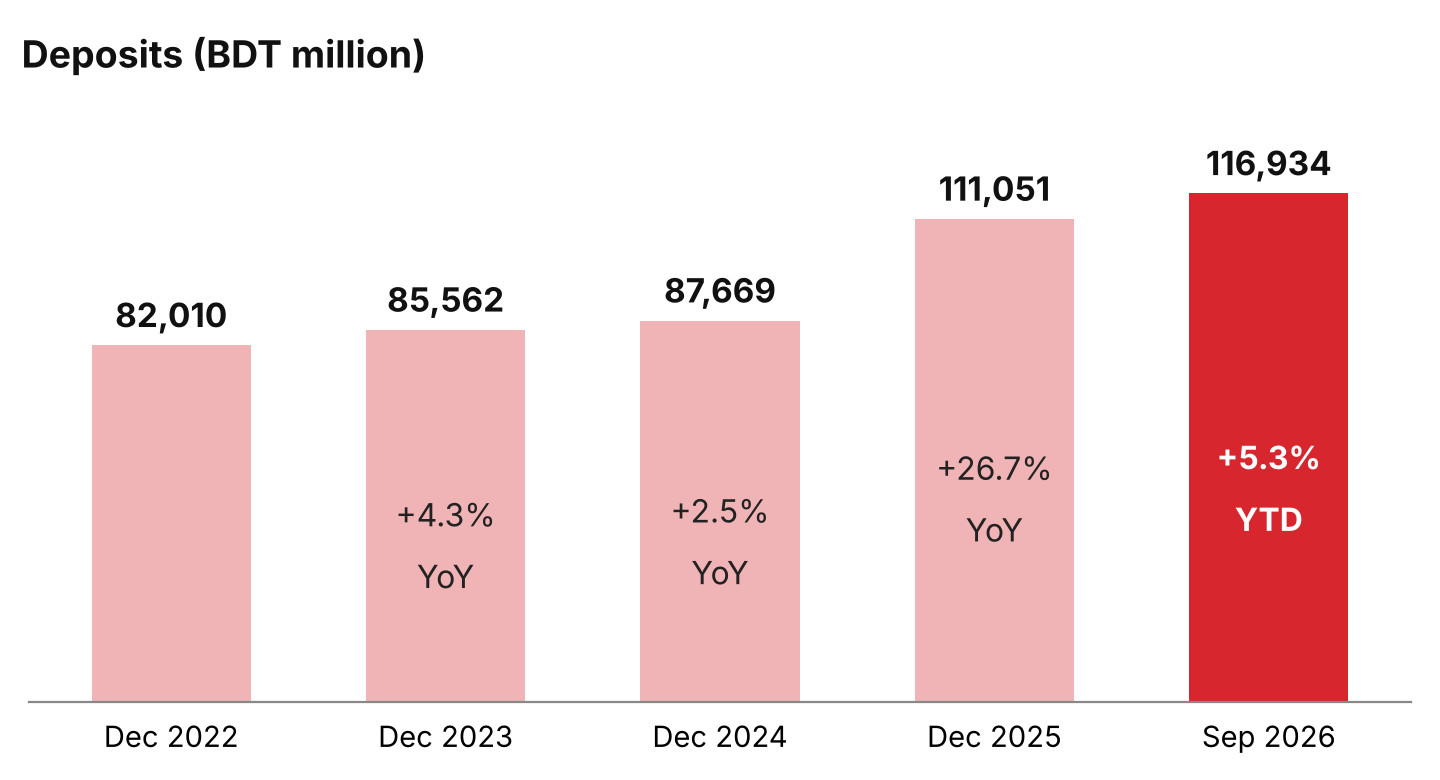
IDLC Finance’s deposits rose 5.3% to BDT 116,934.3 million as at 30 September 2026 from BDT 111,051.0 million at the end of December 2025, adding BDT 5,883.3 million in nine months. Compared with September 2025, deposits were up 8.3%. On a year-end basis, deposits grew 4.3% in 2023 and 2.5% in 2024 before jumping 26.7% in 2025, when the company added BDT 23,381.9 million.
Term deposits, including Mudarabah term deposits, rose 5.4% to BDT 112,738.7 million and made up 96.4% of total deposits, with Mudarabah deposits up 3.9% to BDT 4,590.5 million. Refundable deposits from lease and loan clients grew 3.8% to BDT 4,195.6 million. With deposits rising while the loan book shrank, the loan-to-deposit ratio eased to 103.0% from 109.8% in December 2025. The company also reduced its reliance on borrowings, which fell 17.0% to BDT 26,553.9 million.
Net Interest Income Falls 10.3%
Net interest income (NII) declined 10.3% year-on-year to BDT 2,370.5 million in 9M 2026, following a 21.9% fall in 9M 2025. Interest income rose only 3.4% to BDT 12,456.7 million, as income from loans, advances and leases was broadly flat (up 0.6%) at BDT 11,215.4 million, while interest earned on placements with other banks and financial institutions rose 44.6% to BDT 1,167.6 million. Interest expenses grew faster, by 7.3% to BDT 10,086.2 million. Interest paid on term deposits rose 4.3% to BDT 8,569.0 million and interest on borrowings and placements climbed 37.4% to BDT 1,382.9 million.
Investment income became the company’s largest earnings source, rising 40.0% to BDT 2,674.8 million and accounting for 48.9% of total operating income, up from 38.2% a year earlier. Income from investment in bonds surged 81.2% to BDT 2,127.7 million, making up 79.5% of investment income, up from 61.5%, as the company’s holdings of government securities grew 16.5% to BDT 34,339.2 million from December 2025. In contrast, gains on the sale of government treasury bonds fell 28.6% to BDT 263.7 million, gains on the sale of marketable securities dropped 25.7% to BDT 232.8 million and dividend income declined 22.5% to BDT 40.8 million. The company also earned BDT 9.8 million from investment in Sukuk.
As a result, total operating income increased by BDT 470.6 million, or 9.4%, to BDT 5,473.6 million. The BDT 764.8 million rise in investment income more than offset the BDT 272.3 million drop in NII and a 3.6% decline in other operating income to BDT 426.8 million, the latter mainly due to a 10.3% fall in application, processing and documentation fees.
Salaries Drive a 6.3% Rise in Operating Expenses
Operating expenses rose 6.3% to BDT 2,291.6 million, an increase of BDT 136.1 million. Salaries and allowances were the main driver, rising 11.1% to BDT 1,484.6 million, an increase of BDT 148.5 million, which exceeded the total rise in costs. Depreciation and repairs of company assets also rose 18.5% to BDT 242.1 million. These were partly offset by a 12.2% fall in other expenses to BDT 343.1 million, mainly due to an 87.6% drop in portfolio management charges to BDT 7.4 million, along with lower bank charges and car expenses. With income growing faster than costs, the cost-to-income ratio improved to 41.9% from 43.1%, and profit before provisions grew 11.7% to BDT 3,182.0 million.
Higher Provisions and Tax Limit Net Profit Growth to 4.0%
Total provisions rose 12.4% to BDT 591.6 million. Specific provision for loans increased 3.9% to BDT 528.2 million and general provision rose 20.6% to BDT 63.4 million.
Profit before tax grew 11.6% to BDT 2,590.5 million. However, tax provision rose faster, by 22.4% to BDT 1,171.2 million, pushing the effective tax rate up to 45.2% from 41.2%. Net profit therefore increased 4.0% to BDT 1,419.2 million.
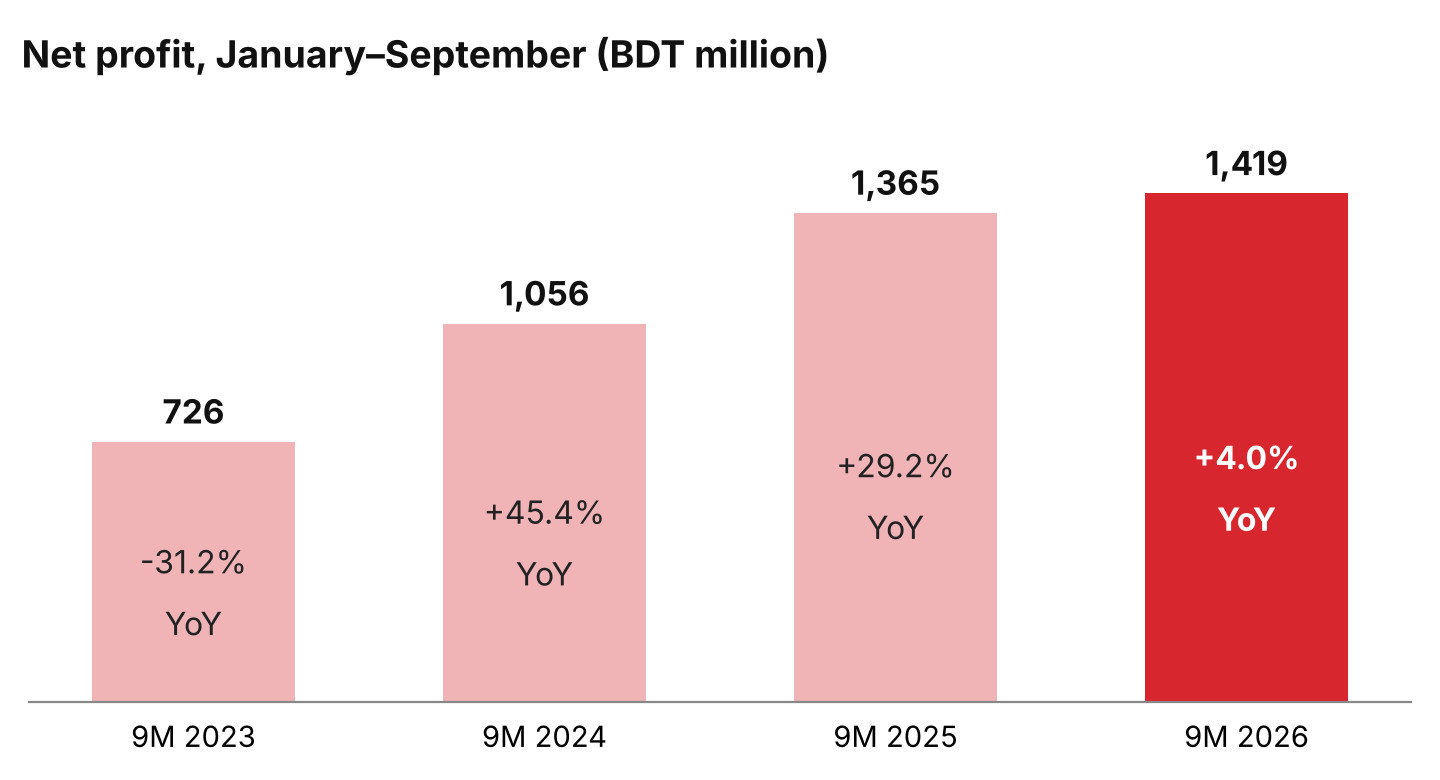
This is the company’s highest nine-month profit in the four-year review period, with net profit growing at a compound annual rate of 25.0% since 9M 2023, though the pace of growth has slowed from 45.4% in 9M 2024 and 29.2% in 9M 2025.
Q3 Net Profit Dips 1.5%
In the third quarter (July–September 2026) alone, total operating income fell 5.0% year-on-year to BDT 1,704.7 million. NII rose 3.2% to BDT 839.3 million, but investment income declined 13.7% to BDT 716.5 million. Operating expenses grew 1.7% to BDT 807.6 million, causing profit before provisions to drop 10.3% to BDT 897.1 million. A 40.6% fall in provisions to BDT 134.8 million cushioned the impact, and net profit for the quarter slipped 1.5% to BDT 464.0 million from BDT 471.0 million, contributing 32.7% of the company’s nine-month profit.
On a consolidated basis, IDLC Finance PLC and its subsidiaries reported a net profit of BDT 2,067.2 million in 9M 2026, up 17.3% from BDT 1,762.8 million in 9M 2025.


Leave a comment