







City Bank PLC, one of Bangladesh’s leading private commercial banks, reported a standalone net profit of BDT 8,560.4 million for the first nine months (9M) of 2026, marking a 21.2% year-on-year increase from BDT 7,061.5 million in the same period of 2025. The earnings growth was driven by a near doubling of net interest income, higher interest earnings on an expanded government securities portfolio and stronger fee and exchange income, along with a lower provision charge against loans.
Loan Book Grows 7.7% Since December to BDT 545,084.1 Million
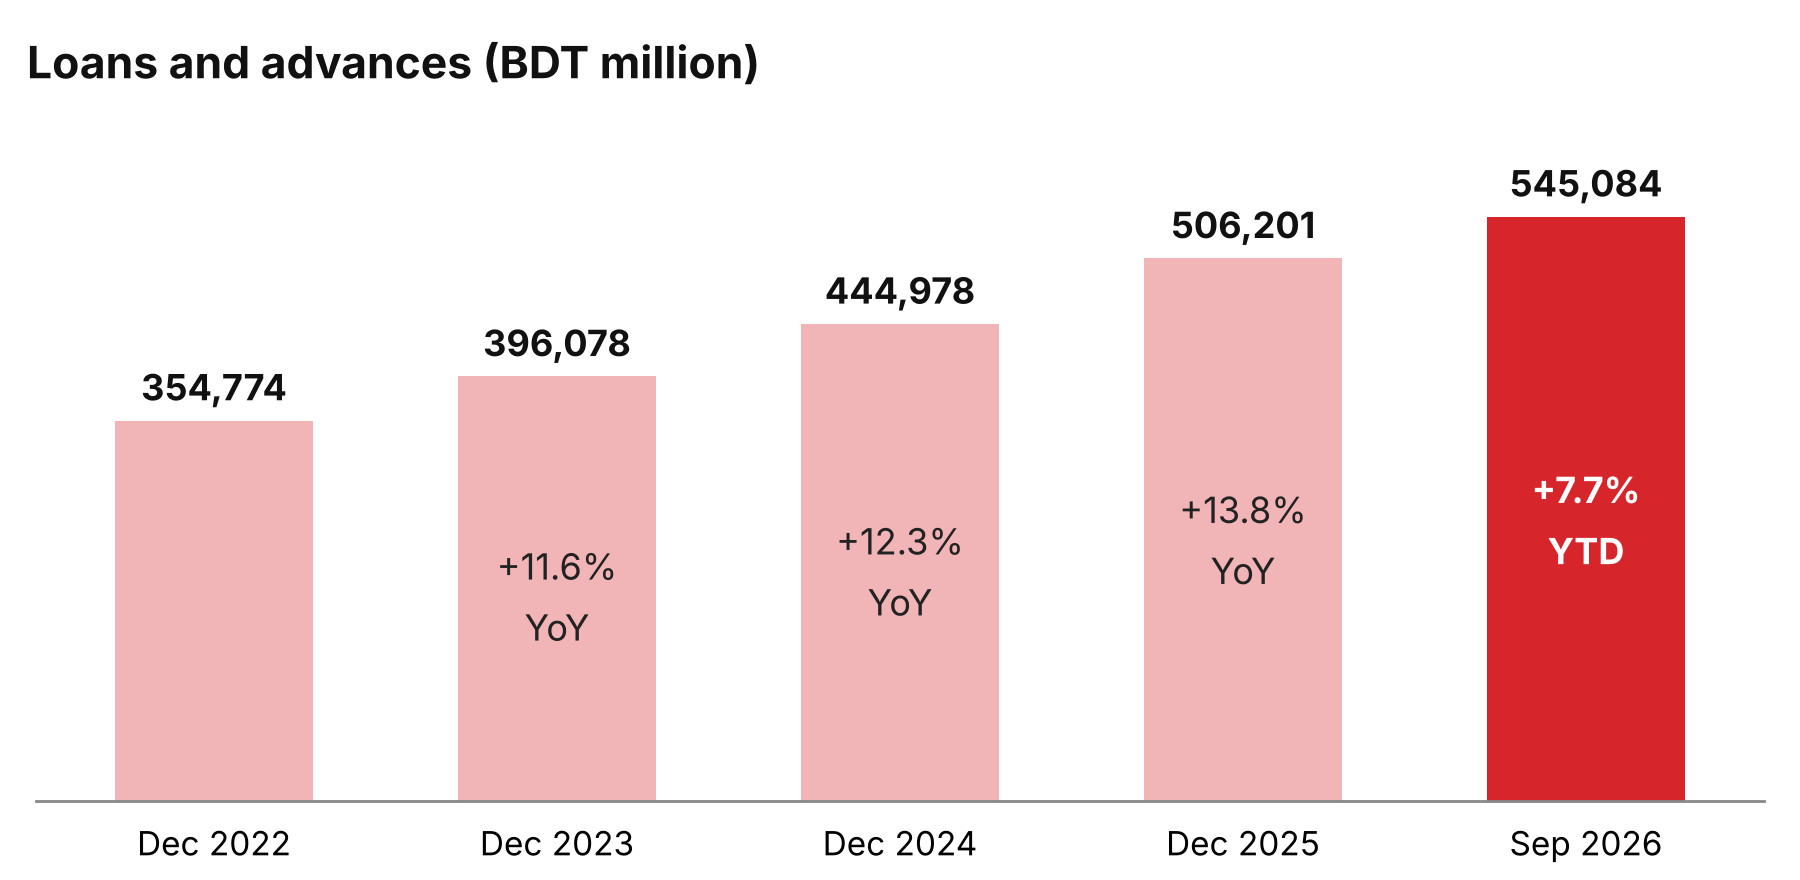
City Bank’s loans and advances stood at BDT 545,084.1 million as at 30 September 2026, up 7.7% from BDT 506,201.2 million at the end of December 2025, adding BDT 38,882.8 million in nine months. Compared with September 2025, the loan book was up 5.5%. On a year-end basis, loans grew 11.6% in 2023, 12.3% in 2024 and 13.8% in 2025, showing a steady acceleration in credit growth, with the bank adding BDT 61,223.6 million to its loan book in 2025, its largest annual increase in the review period.
Specific Provision on Classified Loans Falls 47.7%
The provision data in the bank’s financial statements point to an easing in fresh loan stress. Specific provision charged against classified loans fell 47.7% year-on-year to BDT 1,391.9 million in 9M 2026 from BDT 2,662.4 million, which the bank attributes to an improvement in its loan portfolio. Recovery from previously written-off loans also rose 88.4% to BDT 1,051.4 million.
At the same time, the bank continued to build its general reserve. Provision against unclassified loans stood at BDT 5,398.5 million, down 7.8% year-on-year but nearly four times the specific charge, lifting the general provision held as Tier-2 capital to BDT 14,434.3 million as at 30 September 2026, up 23.4% from BDT 11,698.0 million at the end of December 2025.
Deposits Jump 22.6% to BDT 774,124.9 Million
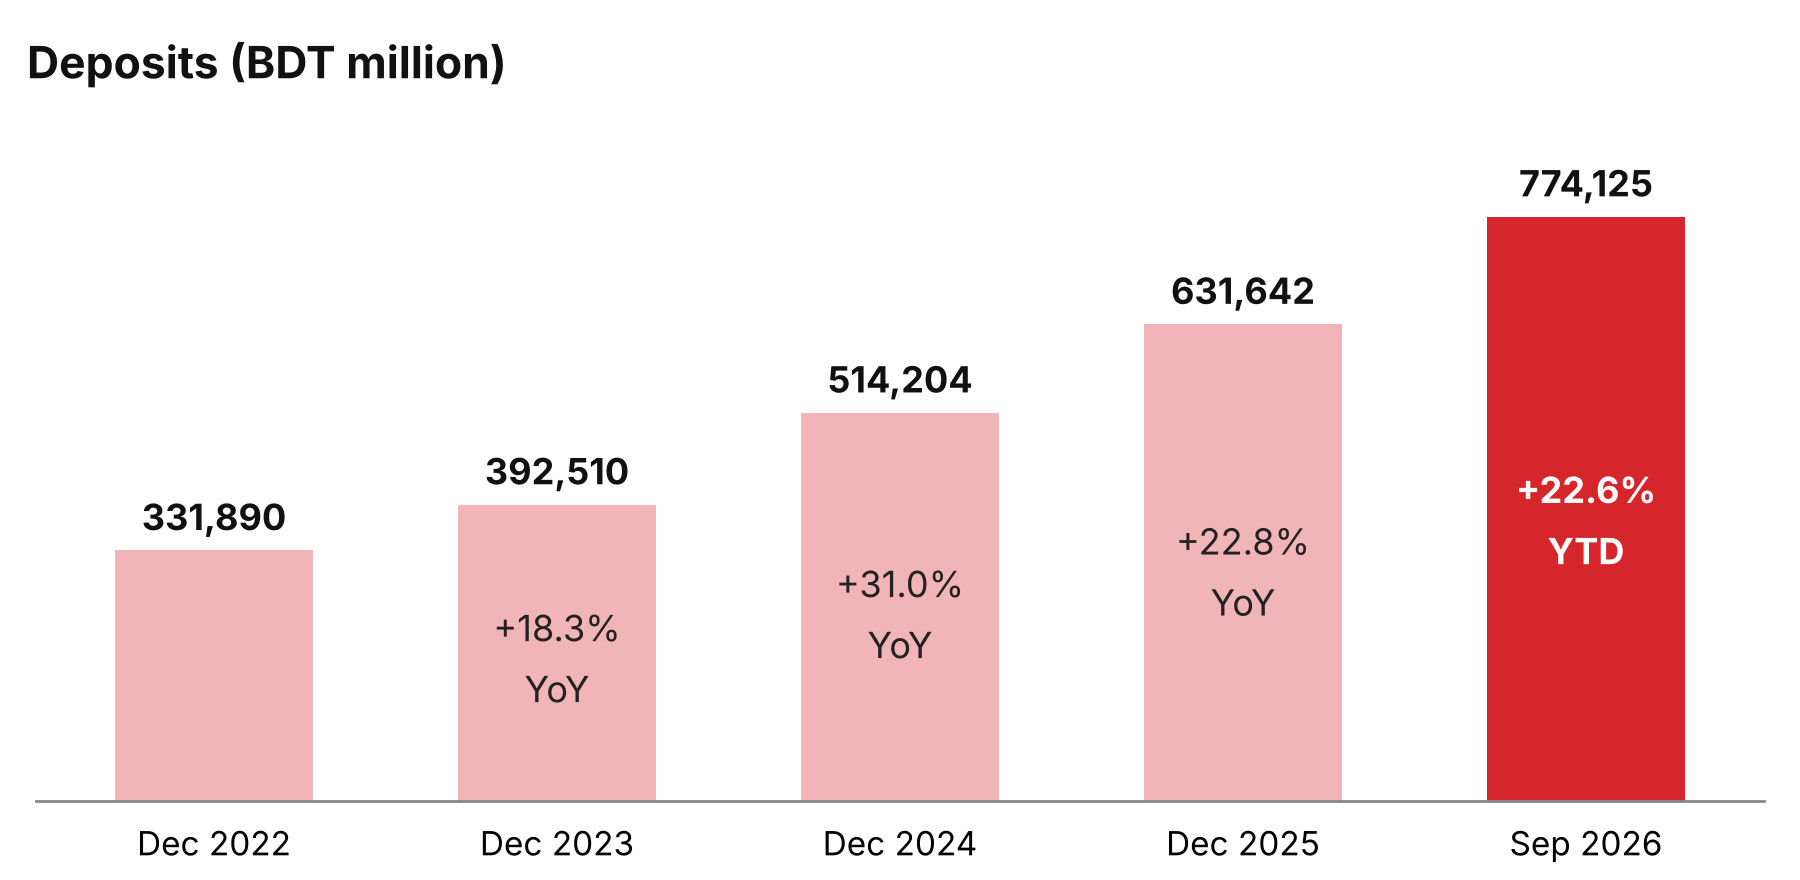
City Bank’s deposits rose 22.6% to BDT 774,124.9 million as at 30 September 2026 from BDT 631,642.4 million at the end of December 2025, adding BDT 142,482.5 million in nine months, more than the bank added in any full year of the review period. Compared with September 2025, deposits were up 22.1%. On a year-end basis, deposits grew 18.3% in 2023, 31.0% in 2024 and 22.8% in 2025, consistently outpacing loan growth.
Since December 2025, fixed deposits recorded the fastest growth among the major categories, rising 25.0% to BDT 449,969.5 million, followed by current and other accounts at 22.5% (BDT 177,225.7 million) and savings deposits at 20.8% (BDT 143,420.1 million), while bills payable fell 58.0% to BDT 3,509.7 million. Low-cost current and savings deposits (CASA) made up 41.4% of total deposits, slightly down from 41.7% at the end of 2025, while fixed deposits remained the largest funding source at 58.1%, up from 57.0%. With deposits growing roughly three times as fast as loans, the gross loan-to-deposit ratio eased to 70.4% from 80.1% in December 2025.
Net Interest Income Nearly Doubles to BDT 3,174.2 Million
Net interest income (NII) grew 93.0% year-on-year to BDT 3,174.2 million in 9M 2026 from BDT 1,644.3 million, recovering partly from an 87.4% plunge in 9M 2025, though it remains well below the BDT 11,568.9 million earned in 9M 2024. Interest income rose 5.7% to BDT 42,442.3 million, which the bank attributes to a higher average volume of loans and advances and an improved yield on advances, while interest expenses rose at a slower 2.0% to BDT 39,268.1 million on the back of deposit growth. Even so, NII accounted for only 7.8% of total operating income.
Investment income remained the bank’s largest earnings source, rising 8.3% to BDT 29,696.2 million and accounting for 72.8% of total operating income, down from 76.9% a year earlier. Interest on treasury bills, bonds and reverse repo increased 16.8% to BDT 24,888.6 million, making up 83.8% of investment income, up from 77.7%, as the bank’s holdings of government securities jumped 77.2% to BDT 336,040.8 million from BDT 189,599.9 million in December 2025. In contrast, gains on government securities fell 31.3% to BDT 3,794.4 million and gains on the sale of shares and debentures dropped 27.0% to BDT 160.3 million, while dividend income on shares quadrupled to BDT 564.0 million from BDT 140.9 million and interest on non-convertible bonds rose 141.2% to BDT 142.0 million.
As a result, total operating income increased by BDT 5,097.6 million, or 14.3%, to BDT 40,767.4 million. Investment income contributed 44.5% of this increase, NII 30.0% and commission, exchange and brokerage income, which rose 20.8% to BDT 7,645.1 million on a 44.9% jump in exchange gains and a 25.7% rise in other fees and charges, 25.8%.
Salaries and Other Expenses Push Operating Expenses Up 22.0%
Operating expenses rose 22.0% to BDT 18,348.9 million, an increase of BDT 3,310.2 million. Salaries and allowances were the main driver, rising 17.5% to BDT 10,225.6 million and accounting for 46.0% of the total increase. Other expenses grew 38.2% to BDT 3,292.2 million and depreciation and repairs of bank assets rose 27.5% to BDT 3,042.8 million, together contributing a further 47.3% of the increase. With costs growing faster than income, the cost-to-income ratio rose to 45.0% from 42.2%, and profit before provisions grew a modest 8.7% to BDT 22,418.5 million.
Lower Provisions Lift Net Profit 21.2%
Total provisions fell 15.4% to BDT 7,475.5 million. Provision for loans and advances declined 20.3% to BDT 6,790.4 million, led by the sharp drop in specific provision on classified loans. This was partly offset by a rise in provision for off-balance sheet exposures to BDT 367.9 million from BDT 167.6 million and in other provisions to BDT 540.3 million from BDT 189.8 million, while the bank wrote back BDT 223.0 million on investments, compared with BDT 42.4 million a year earlier.
Profit before tax grew 26.7% to BDT 14,943.0 million. Tax provision rose faster, by 34.8% to BDT 6,382.6 million, including a deferred tax charge of BDT 963.8 million against a credit of BDT 78.5 million a year earlier, pushing the effective tax rate up to 42.7% from 40.1%. Net profit therefore increased 21.2% to BDT 8,560.4 million.
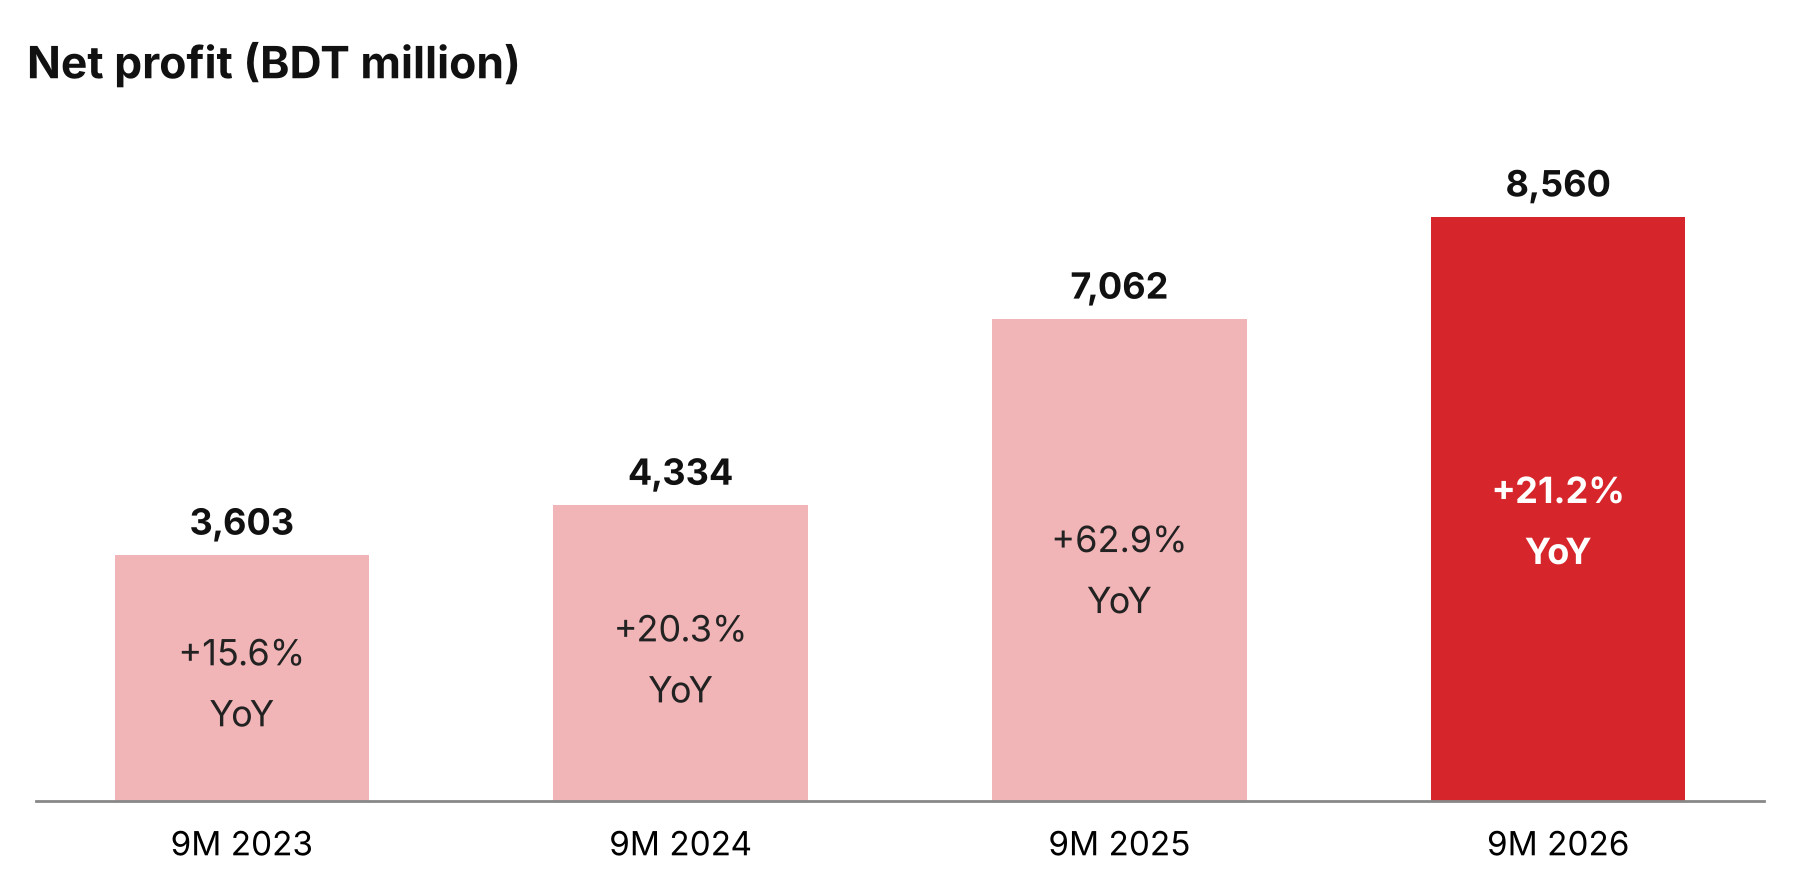
This is the bank’s highest nine-month profit in the four-year review period, with net profit growing at a compound annual rate of 33.4% since 9M 2023.
Q3 Net Profit Falls 16.4%
In the third quarter (July–September 2026) alone, total operating income rose 9.8% year-on-year to BDT 14,569.6 million. NII turned positive at BDT 973.7 million from a negative BDT 222.3 million a year earlier, as interest income rose 6.3% while interest expenses fell 2.4%, and commission, exchange and brokerage income grew 16.3% to BDT 2,684.0 million. However, investment income slipped 2.5% to BDT 10,823.4 million. Operating expenses grew 18.9%, limiting the rise in profit before provisions to 3.7% at BDT 8,202.8 million. With provisions up 17.6% to BDT 2,827.1 million and tax provision up 36.2% to BDT 1,999.4 million, net profit for the quarter fell 16.4% to BDT 3,376.3 million from BDT 4,039.8 million, contributing 39.4% of the bank’s nine-month profit.
On a consolidated basis, City Bank PLC and its subsidiaries reported a net profit of BDT 8,671.8 million in 9M 2026, up 20.1% from BDT 7,221.9 million in 9M 2025.


Leave a comment