







Eastern Bank PLC, one of Bangladesh’s leading private commercial banks, reported a standalone net profit of BDT 6,640.0 million for the first nine months (9M) of 2026, marking a 5.9% year-on-year increase from BDT 6,267.8 million in the same period of 2025. The earnings growth was primarily driven by a sharp rise in investment income, particularly from government securities, which more than offset a steep fall in net interest income and higher provisions against loans.
Eastern Bank | Loan Book Shrinks 3.4% Since December to BDT 460,678.4 Million
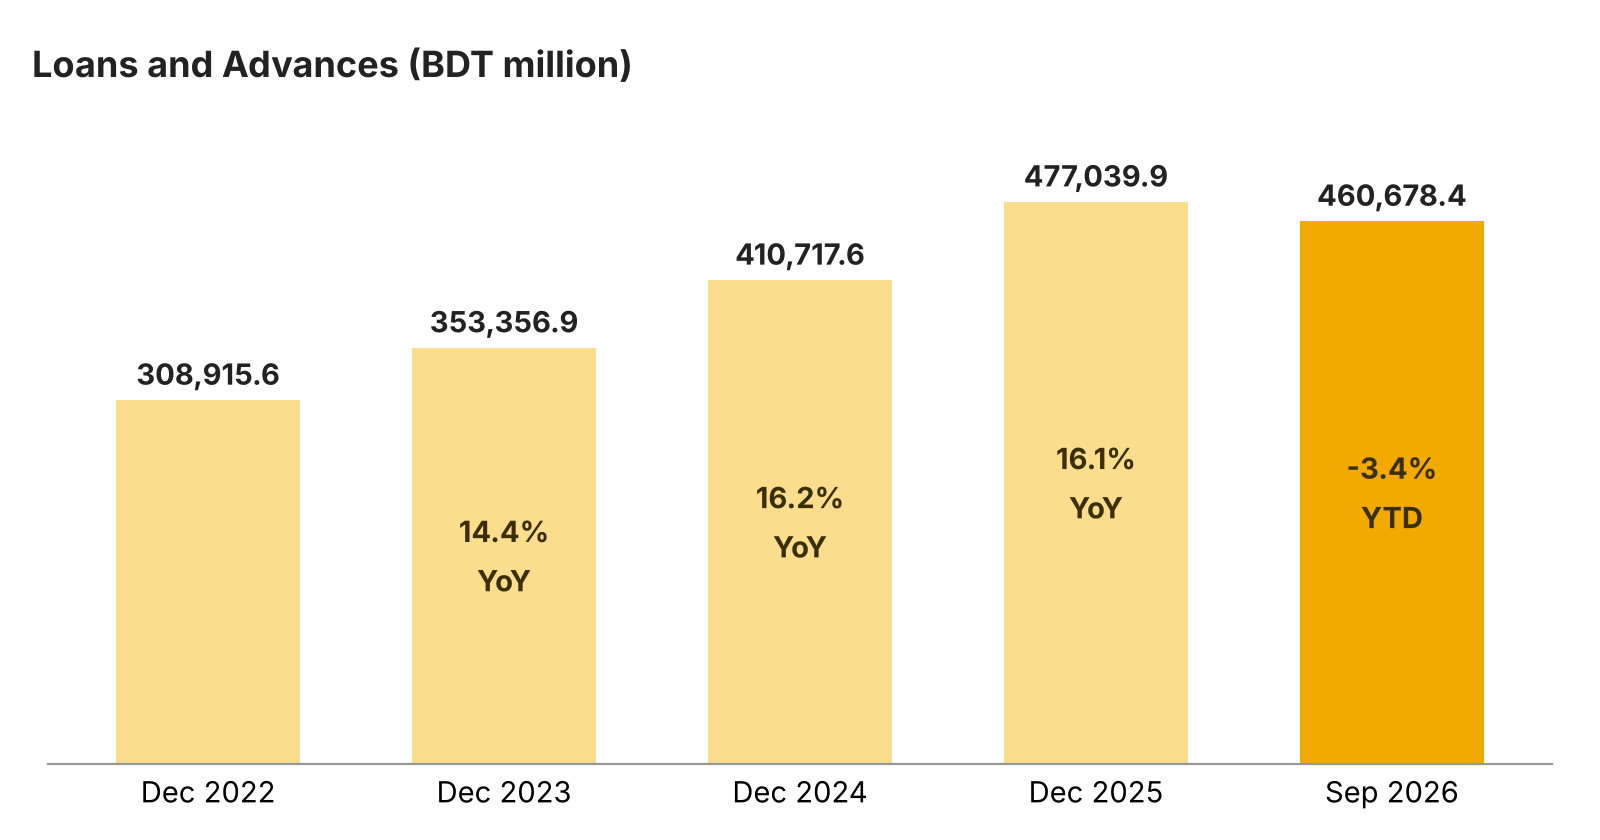
Eastern Bank’s loans and advances stood at BDT 460,678.4 million as at 30 September 2026, down 3.4% from BDT 477,039.9 million at the end of December 2025, a reduction of BDT 16,361.5 million in nine months. Compared with September 2025, the loan book was up 2.7%. On a year-end basis, loans grew 14.4% in 2023, 16.2% in 2024 and 16.1% in 2025, adding more than BDT 44,000 million in each of those years, making the nine-month contraction a clear break from the bank’s steady mid-teens credit growth.
NPL Ratio Rises to 3.70% as Classified Loans Jump 59.7%
Eastern Bank’s total non-performing loans (NPLs), comprising sub-standard, doubtful and bad/loss loans, stood at BDT 17,052.6 million as at 30 September 2026, up 59.7% from BDT 10,675.3 million at the end of December 2025, an addition of BDT 6,377.3 million. With NPLs rising while the loan book shrank, the NPL ratio climbed to 3.70% from 2.24%. On a year-end basis, the ratio had risen from 2.78% in December 2022 to 3.10% in December 2023 and 3.34% in December 2024, before improving to 2.24% in December 2025, when total NPLs fell 22.2%.
Classification | Dec 2022 | Dec 2023 | Dec 2024 | Dec 2025 | Sep 2026 | YTD Growth |
|---|---|---|---|---|---|---|
Sub-standard | 1,351.8 | 1,152.3 | 4,086.3 | 1,080.6 | 4,739.6 | 338.6% |
Doubtful | 594.3 | 876.5 | 591.5 | 2,004.0 | 3,881.4 | 93.7% |
Bad/Loss | 6,633.0 | 8,912.3 | 9,040.1 | 7,590.6 | 8,431.6 | 11.1% |
Total NPL | 8,579.1 | 10,941.1 | 13,718.0 | 10,675.3 | 17,052.6 | 59.7% |
NPL ratio | 2.78% | 3.10% | 3.34% | 2.24% | 3.70% | – |
Source: Eastern Bank PLC standalone financial statements. Year-end balances as at 31 December and latest as at 30 September 2026, in BDT million. YTD growth = Sep 2026 vs Dec 2025.
The increase came mostly from the early-stage categories. Sub-standard loans more than quadrupled (up 338.6%) to BDT 4,739.6 million since December 2025, accounting for 57.4% of the total rise in NPLs, while doubtful loans nearly doubled (up 93.7%) to BDT 3,881.4 million. Together, these two categories now make up 50.6% of total NPLs, up from 28.9% at the end of 2025. Bad/loss loans rose a more modest 11.1% to BDT 8,431.6 million, reducing their share of total NPLs to 49.4% from 71.1%. The bank attributed its higher loan provisions mainly to the downgrading of existing classified loans.
The watch list also points to further pressure. Loans in the special mention account (SMA), the stage before classification, rose 58.3% to BDT 18,854.0 million, and the interest suspense account increased 35.6% to BDT 6,822.0 million. On the positive side, recovery from previously written-off loans rose 22.8% to BDT 400.6 million in 9M 2026. Total provisions held against loans and off-balance sheet exposures stood at BDT 19,362.4 million, equivalent to 113.5% of NPLs.
Deposits Grow 13.3% to BDT 630,658.4 Million
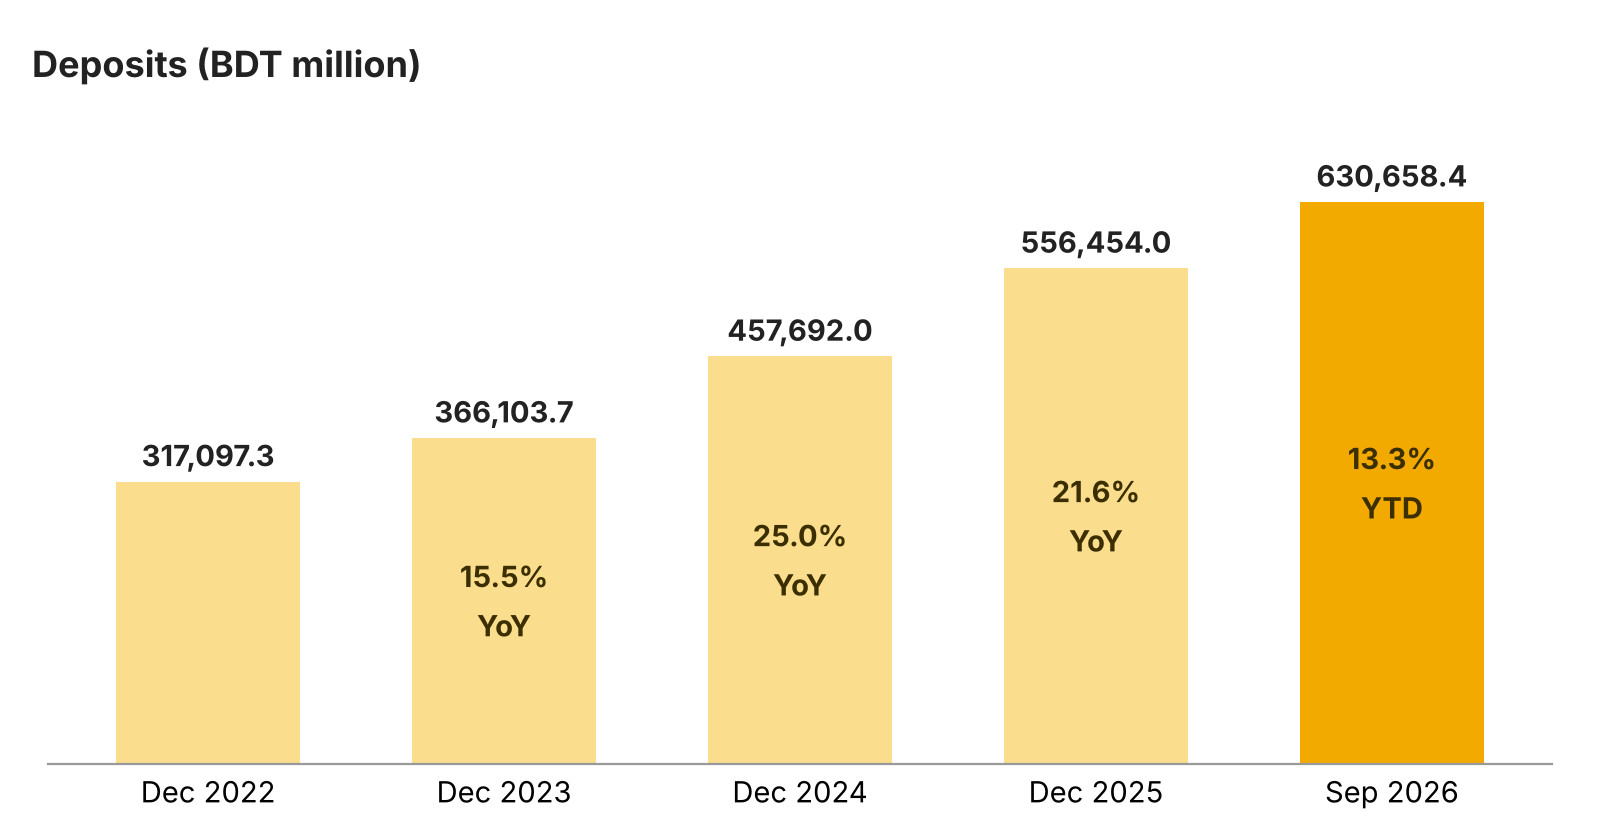
Eastern Bank’s deposits rose 13.3% to BDT 630,658.4 million as at 30 September 2026 from BDT 556,454.0 million at the end of December 2025, adding BDT 74,204.4 million in nine months. Compared with September 2025, deposits were up 21.4%. On a year-end basis, deposits grew 15.5% in 2023, 25.0% in 2024 and 21.6% in 2025, consistently outpacing loan growth.
Since December 2025, term deposits recorded the fastest growth among the major categories, rising 20.9% to BDT 366,412.1 million, followed by savings deposits at 11.5% (BDT 96,592.8 million) and current and other accounts at 8.5% (BDT 77,725.5 million), while special notice deposits fell 6.1% to BDT 87,920.8 million. As a result, term deposits strengthened their position as the largest funding source at 58.1% of total deposits, up from 54.5%, while low-cost current and savings deposits (CASA) slipped to 27.6% from 28.4%. With deposits rising while the loan book shrank, the gross loan-to-deposit ratio dropped sharply to 73.0% from 85.7% in December 2025.
Net Interest Income Plunges 79.6%
Net interest income (NII) fell 79.6% year-on-year to BDT 1,502.6 million in 9M 2026 from BDT 7,348.7 million, following an 8.8% decline in 9M 2025. Interest income slipped 3.7% to BDT 34,628.8 million, as interest on loans and advances was broadly flat (down 0.5%) at BDT 33,756.1 million and income from placements with banks and financial institutions and call money lending nearly halved. Interest expenses, meanwhile, rose 15.7% to BDT 33,126.1 million. Interest paid on deposits climbed 21.5% to BDT 27,191.7 million, led by a 20.4% rise in interest on fixed deposits to BDT 20,824.8 million, and interest on subordinated bonds more than doubled to BDT 1,019.7 million, which outweighed a 78.0% drop in inter-bank repo costs.
Investment income became the bank’s largest earnings source by a wide margin, rising 68.3% to BDT 18,477.5 million and accounting for 73.4% of total operating income, up from 47.7% a year earlier. Interest on government securities surged 74.9% to BDT 16,949.6 million, making up 91.7% of investment income, up from 88.3%, as the bank’s holdings of government securities grew 42.0% to BDT 276,602.0 million from BDT 194,845.2 million in December 2025. Within this, interest on treasury bonds more than doubled (up 103.8%) to BDT 9,822.9 million, amortisation gains on treasury bills rose 45.5% to BDT 3,807.6 million and profit from Sukuk jumped to BDT 1,132.7 million from BDT 322.2 million, while interest on reverse repo also more than doubled to BDT 683.4 million. In contrast, interest on corporate and subordinated bonds fell 44.8% to BDT 249.6 million and dividend income declined 5.1% to BDT 627.3 million.
As a result, total operating income increased by BDT 2,115.4 million, or 9.2%, to BDT 25,157.2 million. The BDT 7,497.0 million rise in investment income and a 10.8% increase in commission, exchange and brokerage income to BDT 4,832.8 million more than offset the BDT 5,846.1 million fall in NII.
Salaries Drive a 10.0% Rise in Operating Expenses
Operating expenses rose 10.0% to BDT 10,435.3 million, an increase of BDT 948.9 million. Salaries and allowances were the main driver, rising 12.7% to BDT 6,564.3 million and accounting for 78.0% of the total increase. Depreciation and repairs of bank assets rose 10.0% to BDT 1,423.7 million and rent, taxes, insurance and utilities increased 20.5% to BDT 628.5 million, together contributing a further 25.0% of the increase. These were partly offset by a 3.0% fall in other operating expenses to BDT 775.0 million. With income and costs growing at a similar pace, the cost-to-income ratio was broadly steady at 41.5% against 41.2%, and profit before provisions grew 8.6% to BDT 14,721.9 million.
Higher Loan Provisions Limit Net Profit Growth to 5.9%
Total provisions rose 19.7% to BDT 3,672.4 million. Specific provision for loans and advances, net of recoveries from written-off loans, jumped 67.6% to BDT 3,591.7 million, reflecting the downgrading of classified loans. This was partly offset by a 91.1% fall in general provision on loans to BDT 78.3 million from BDT 878.1 million as the loan book contracted, although general provision for off-balance sheet exposures rose to BDT 311.7 million from BDT 114.6 million. Total provision for loans and off-balance sheet exposures therefore increased 27.0% to BDT 3,981.6 million. The bank also wrote back BDT 309.2 million under other provisions, mainly a BDT 317.0 million release on the revaluation of equity securities.
Profit before tax grew 5.4% to BDT 11,049.5 million. Tax provision rose a slower 4.5% to BDT 4,409.5 million, as a lower current tax charge was largely offset by a smaller deferred tax income, bringing the effective tax rate to 39.9% from 40.2%. Net profit therefore increased 5.9% to BDT 6,640.0 million.
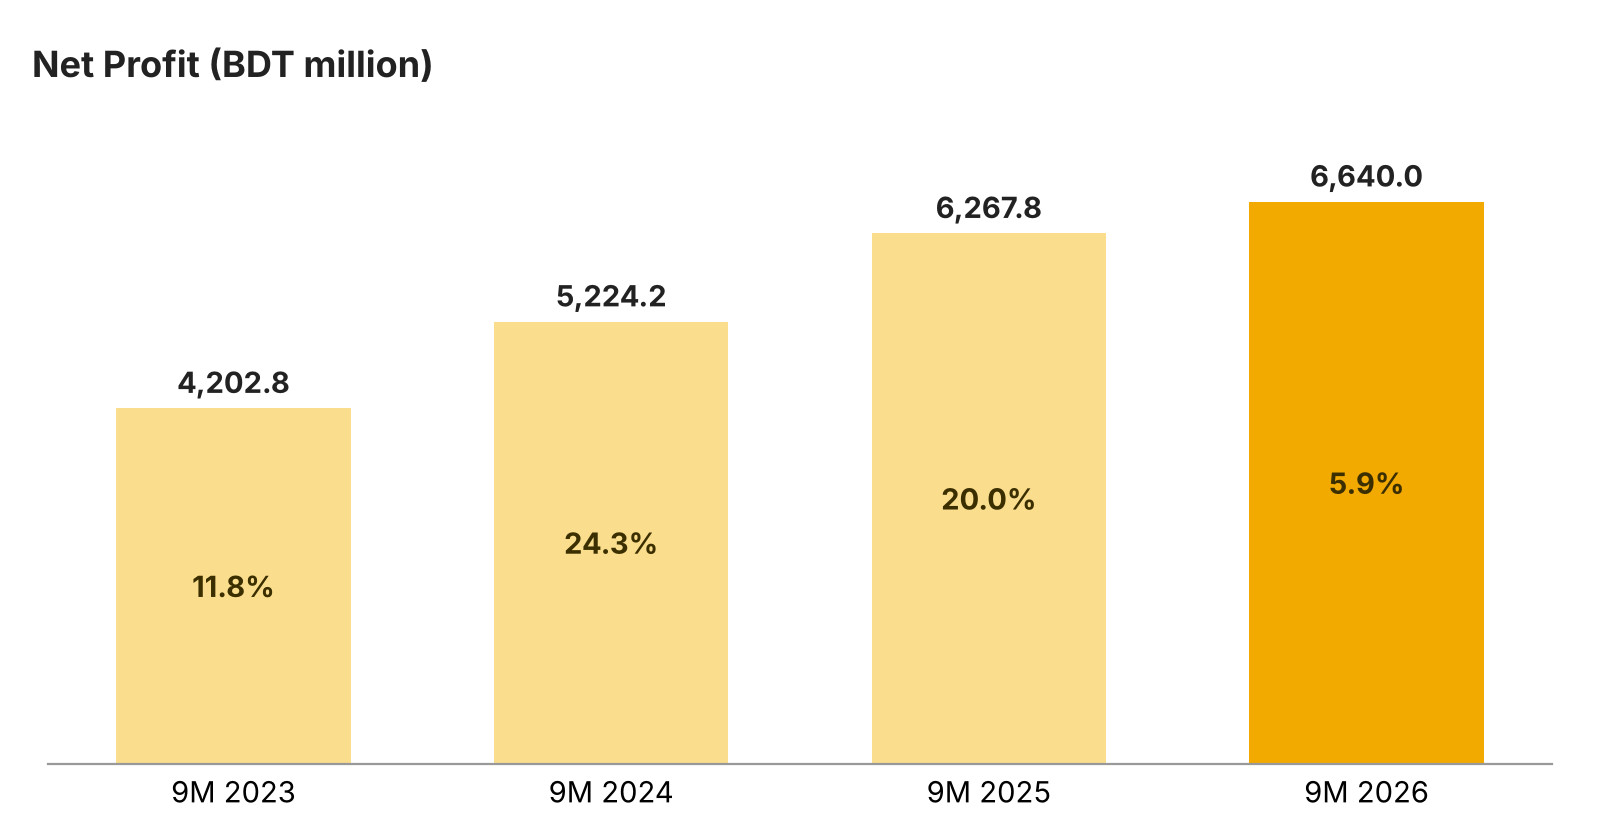
This is the bank’s highest nine-month profit in the four-year review period, with net profit growing at a compound annual rate of 16.5% since 9M 2023, though the pace of growth has slowed from 24.3% in 9M 2024 and 20.0% in 9M 2025.
Q3 Net Profit Slips 2.2%
In the third quarter (July–September 2026) alone, total operating income rose 10.5% year-on-year to BDT 8,687.1 million. Investment income more than doubled (up 104.3%) to BDT 7,248.7 million, while NII turned negative at BDT 455.0 million from a positive BDT 2,431.4 million a year earlier, as interest income fell 8.3% and interest expenses rose 19.1%. Operating expenses grew 8.7%, lifting profit before provisions by 11.6% to BDT 5,318.9 million. However, provisions surged to BDT 2,012.6 million from BDT 337.6 million, driven by specific provision of BDT 1,744.7 million against BDT 545.5 million, pulling profit before tax down 25.3% to BDT 3,306.2 million. A 52.7% lower tax charge cushioned the impact, and net profit for the quarter slipped 2.2% to BDT 2,349.0 million from BDT 2,402.9 million, contributing 35.4% of the bank’s nine-month profit.
On a consolidated basis, Eastern Bank PLC and its subsidiaries reported a net profit of BDT 6,740.1 million in 9M 2026, up 15.3% from BDT 5,847.2 million in 9M 2025.
For more updates, be with Markedium.



Leave a comment