







MJL Bangladesh PLC, the marketer of Mobil lubricants in Bangladesh and the parent of LPG company Omera Petroleum and cylinder maker Omera Cylinders, has published its consolidated financial statements for the first quarter (Q1) of FY 2026-27. Despite healthy growth in net revenue, net profit after tax fell 25.7% to BDT 714.7 million from BDT 961.4 million in the same quarter last year. Earnings per share dropped to BDT 2.08 from BDT 3.06.
MJL Bangladesh | Double-Digit Revenue Growth
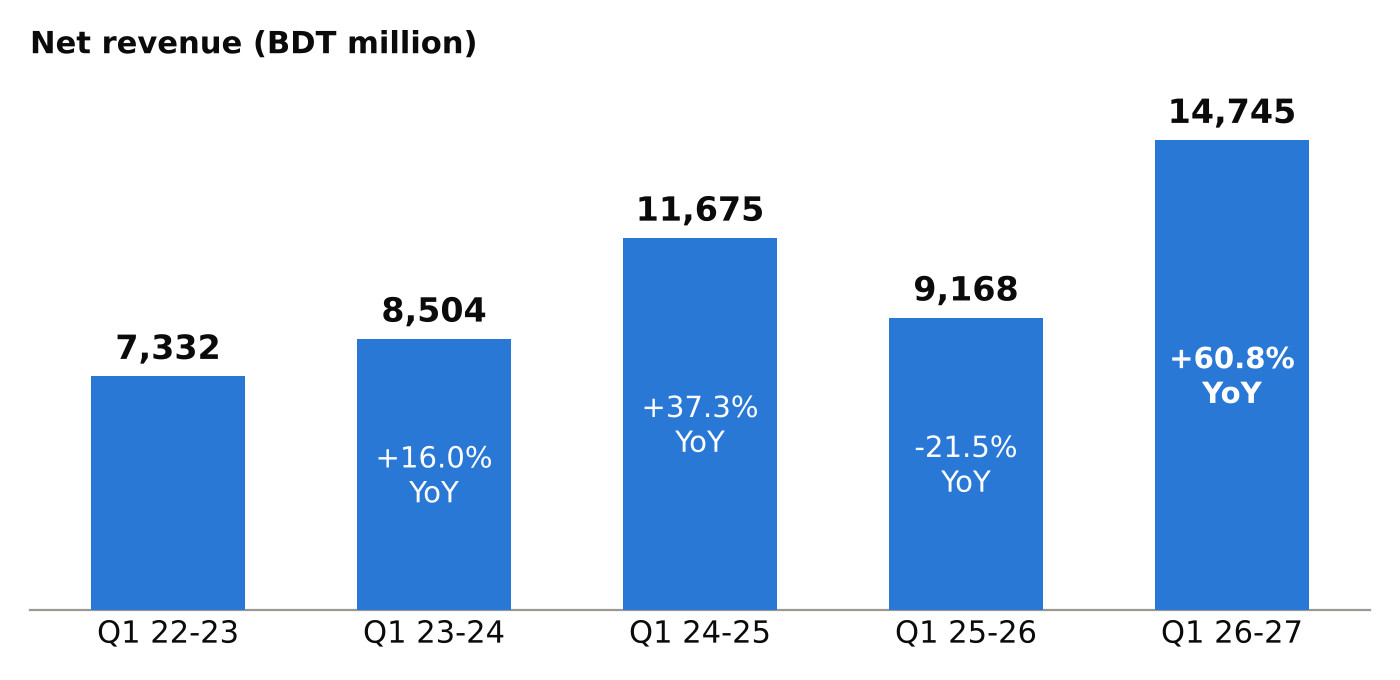
Net revenue of the company grew 60.8% to BDT 14,745.1 million from BDT 9,167.6 million.This is the highest first-quarter revenue in the five years compared, and it more than reverses the 21.5% decline of Q1 FY 2025-26. Since Q1 FY 2022-23, net revenue has grown at a compound annual rate of 19.1%.
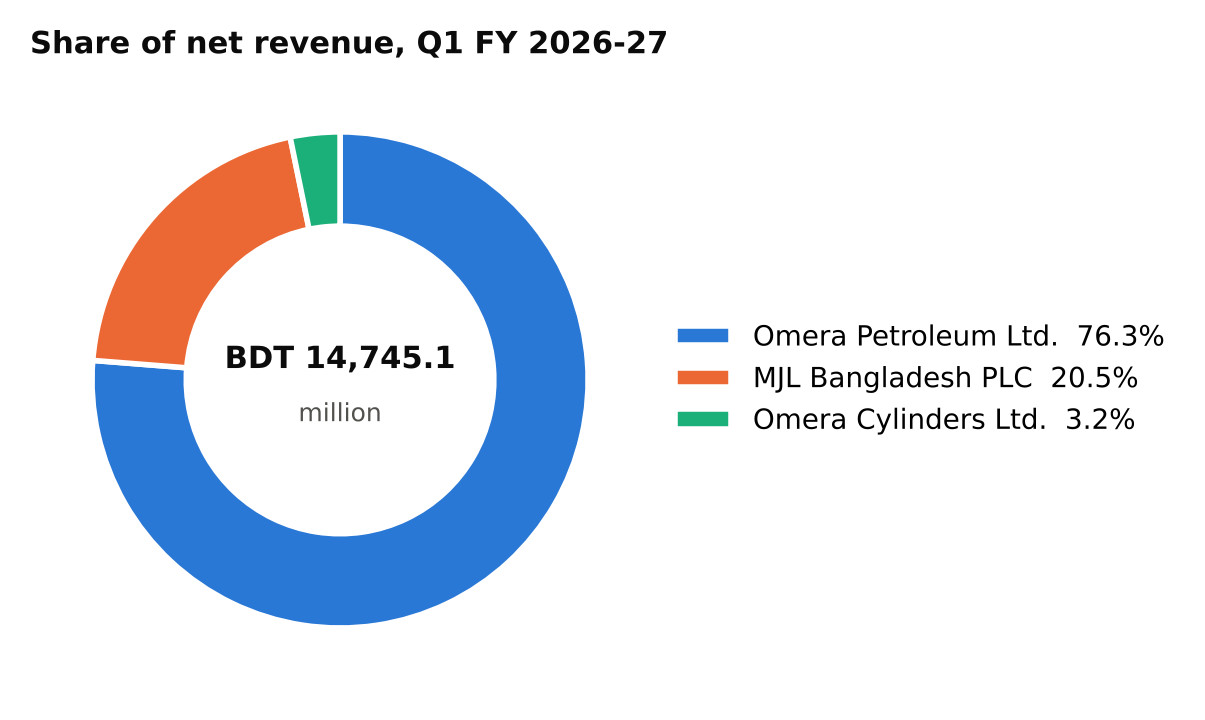
Omera Petroleum Limited (OPL), the LPG arm in which MJL holds 62.5%, is now by far the largest contributor. Its net revenue rose 84.7% to BDT 11,244.0 million, lifting its share of group revenue to 76.3% from 66.4%. Its BDT 5,157.3 million increase made up 92.5% of the group’s growth. Part of this jump comes from Premier LP Gas Limited, which OPL acquired in January 2026 and which was not in the group in Q1 last year.
Omera Cylinders Limited (OCL) went from almost nothing to BDT 475.9 million. Last year, BDT 227.8 million of its BDT 245.3 million cylinder sales went to OPL and were eliminated on consolidation. This year, only BDT 110.0 million of its BDT 585.9 million sales went to OPL, so most of its revenue now comes from outside customers. MJL Bangladesh PLC on its own slipped 1.2% to BDT 3,025.2 million, and its share fell to 20.5% from 33.4%.
Company (BDT million) | Q1 26-27 | Q1 25-26 | Growth | Share of revenue |
|---|---|---|---|---|
Omera Petroleum Ltd. | 11,244.0 | 6,086.7 | 84.7% | 76.3% |
MJL Bangladesh PLC | 3,025.2 | 3,063.5 | -1.2% | 20.5% |
Omera Cylinders Ltd. | 475.9 | 17.5 | 2,625.4% | 3.2% |
Total | 14,745.1 | 9,167.6 | 60.8% | 100.0% |
Source: Q1 quarterly reports. Net revenue after adjusting inter-company sales.
Inside MJL, lubricants grew but the oil tanker business fell sharply. Locally blended lubricants rose 8.0% to BDT 1,251.2 million, imported lubricants grew 15.4% to BDT 1,022.8 million, and lubricant exports tripled to BDT 18.0 million. In total, lubricant sales grew 11.8% to BDT 2,291.9 million. However, voyage freight earnings from the two crude oil tankers fell 27.0% to BDT 723.4 million and demurrage earnings nearly halved. The BDT 278.6 million drop in tanker revenue more than wiped out the BDT 241.2 million gain from lubricants.
Company / segment (BDT million) | Q1 26-27 | Q1 25-26 | Growth |
|---|---|---|---|
MJL Bangladesh PLC | 3,025.2 | 3,063.5 | -1.2% |
Locally blended lubricants | 1,251.2 | 1,158.6 | 8.0% |
Imported lubricants | 1,022.8 | 886.3 | 15.4% |
Lubricant exports | 18.0 | 5.8 | 209.3% |
Voyage freight earning | 723.4 | 990.4 | -27.0% |
Demurrage earning | 12.1 | 23.7 | -48.9% |
Inter-company adjustment | (2.3) | (1.3) | – |
Omera Petroleum Ltd. | 11,244.0 | 6,086.7 | 84.7% |
LPG sales | 11,244.2 | 6,086.7 | 84.7% |
Inter-company adjustment | (0.2) | – | – |
Omera Cylinders Ltd. | 475.9 | 17.5 | 2,625.4% |
Cylinder sales | 585.9 | 245.3 | 138.8% |
Inter-company adjustment | (110.0) | (227.8) | – |
Source: Q1 quarterly reports.
Gross Margin Slips to a Five-Year Low
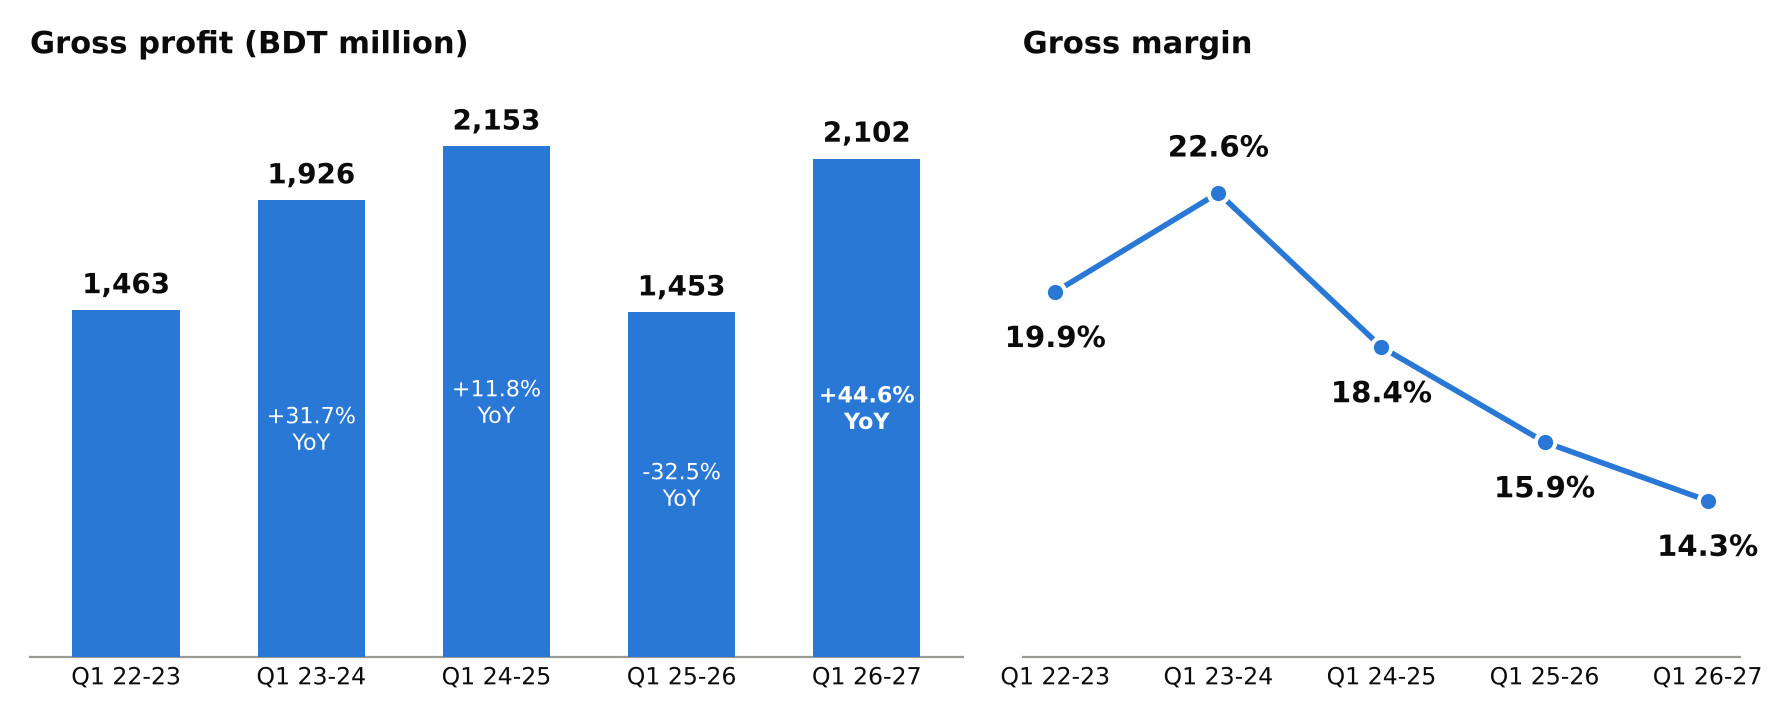
Gross profit rose 44.6% to BDT 2,101.6 million, but it grew more slowly than revenue. As a result, the gross margin fell 160 basis points to 14.3% from 15.9%. This is the lowest Q1 margin in the five years compared and well below the 22.6% of Q1 FY 2023-24. The main reason is the sales mix: LPG, which earns much thinner margins than lubricants, now brings in three-quarters of revenue.
Investment Loss, Finance Costs and Tax Pull Profit Down
Operating profit rose 57.7% to BDT 1,731.9 million, while the operating margin edged down to 11.7% from 12.0%. Administrative and selling expenses grew only 4.1% to BDT 369.7 million, so they fell to 2.5% of revenue from 3.9%.
Employee compensation was the biggest driver, rising BDT 27.7 million (21.8%) to BDT 154.7 million. The increase came entirely from the subsidiaries: OPL’s employee cost jumped 66.2%, partly reflecting the newly added Premier LP Gas, while MJL’s own employee cost fell 18.1%. Office repairs and sales incentives added BDT 6.6 million and BDT 6.4 million respectively. Lower spending on sales promotion (down BDT 7.0 million), advertisement (down BDT 5.5 million) and government fees (down BDT 3.9 million) offset much of this. By company, MJL’s own operating expenses fell 22.0% to BDT 138.7 million, while OPL’s rose 35.6% to BDT 226.9 million.
Expense driver (BDT million) | Q1 26-27 | Q1 25-26 | Change | Growth |
|---|---|---|---|---|
Employee compensation | 154.7 | 127.0 | 27.7 | 21.8% |
Office repairs and renovation | 15.9 | 9.3 | 6.6 | 70.7% |
Sales incentive | 9.0 | 2.6 | 6.4 | 242.0% |
Insurance | 8.6 | 5.2 | 3.3 | 63.8% |
Sales promotion | 27.2 | 34.2 | (7.0) | -20.5% |
Advertisement and publications | (0.3) | 5.1 | (5.5) | – |
Government fees and charges | 3.9 | 7.8 | (3.9) | -49.4% |
Depreciation and amortization | 43.5 | 47.3 | (3.8) | -8.0% |
Total operating expenses | 369.7 | 355.2 | 14.5 | 4.1% |
Source: Q1 quarterly reports.
The trouble started below operating profit. Other income swung to a loss of BDT 24.5 million from a gain of BDT 317.5 million, mainly because the share portfolio posted a BDT 74.6 million loss against a BDT 258.2 million gain last year. Finance charges rose 25.5% to BDT 725.0 million. Interest on long-term loans nearly tripled to BDT 129.7 million from BDT 44.6 million, and last year’s BDT 37.5 million foreign exchange gain turned into a small loss. The company itself cites higher financial charges and lower non-operating income for the lower EPS. Even so, profit before tax grew 17.3% to BDT 982.5 million. No separate WPPF charge is reported in the consolidated statement.
Tax is where the year-on-year comparison breaks down. Current tax rose 14.2% to BDT 278.9 million, but last year a deferred tax credit of BDT 367.9 million turned the total tax line into a net credit of BDT 123.6 million. This year, the deferred credit was only BDT 11.1 million, so total tax came to BDT 267.8 million and the effective tax rate was 27.3%.
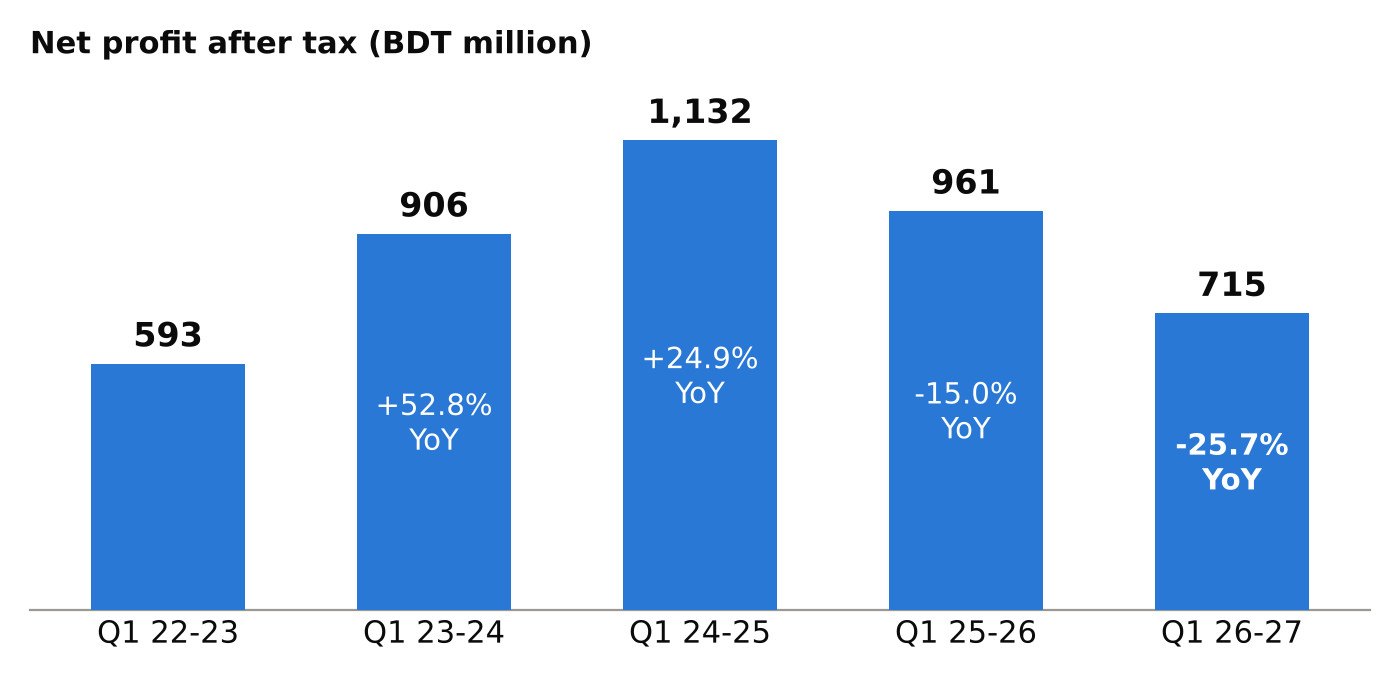
As a result, net profit after tax fell 25.7% to BDT 714.7 million, and the net margin dropped to 4.8% from 10.5%. Profit is now 36.8% below the Q1 FY 2024-25 peak of BDT 1,131.7 million and the lowest since Q1 FY 2022-23.


Leave a comment