







Walton Hi-Tech Industries PLC, one of the leading electronics and home appliance manufacturers in Bangladesh, has published its financial statements for the first quarter (Q1) of FY 2026-27 (July to September 2026). The company earned a net profit of BDT 2,247.4 million, up just 1.7% from BDT 2,208.9 million in the same quarter last year, even though revenue grew 15.7%. Earnings per share rose to BDT 6.74 from a restated BDT 6.63.
Walton | Double-Digit Revenue Growth
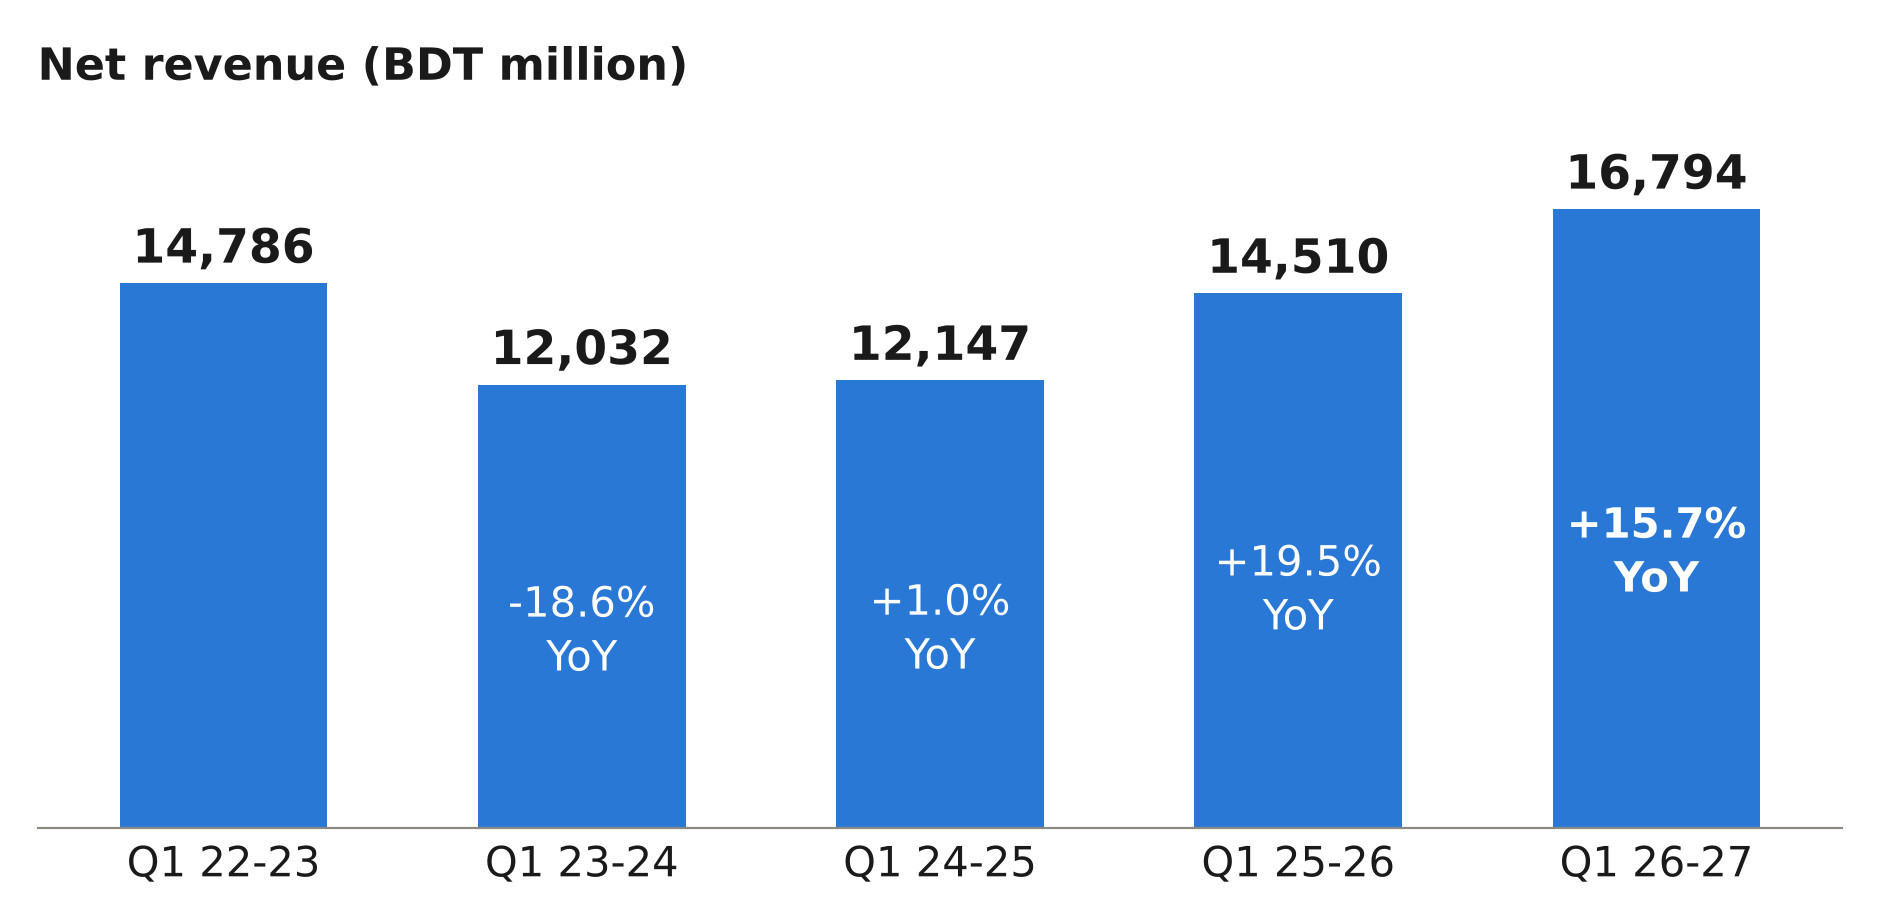
Net revenue grew 15.7% to BDT 16,794.3 million from BDT 14,510.3 million, an increase of BDT 2,284.0 million. Since Q1 FY 2023-24, revenue has grown at a compound annual rate of 11.8%.
Source: Q1 quarterly reports.
Domestic sales remain the backbone of the business. Net domestic sales grew 15.5% to BDT 16,447.7 million and increased BDT 2,213.2 million, or 96.9% of the total revenue increase. A large part of local sales goes through related retail chains: sales to Walton Plaza and WES Plaza, rose 15.1% to BDT 6,115.3 million, about 36.4% of total revenue.
Exports grew faster, up 25.7% to BDT 346.6 million, lifting their share of revenue to 2.1% from 1.9%. Exports have now grown for three straight years from just BDT 36.8 million in Q1 FY 2023-24, but they are still below the BDT 560.1 million earned in Q1 FY 2022-23.
Revenue by market | Q1 26-27 | Q1 25-26 | Growth | Share |
|---|---|---|---|---|
Domestic sales (net) | 16,447.7 | 14,234.5 | 15.5% | 97.9% |
Export sales | 346.6 | 275.8 | 25.7% | 2.1% |
Total revenue | 16,794.3 | 14,510.3 | 15.7% | 100.0% |
Source: Q1 quarterly reports. Values in BDT million.
Gross Margin Holds Steady at 32.3%
Gross profit rose 16.0% to BDT 5,426.3 million, as cost of goods sold grew 15.6% to BDT 11,368.0 million, almost the same pace as revenue. The gross margin edged up 6 basis points to 32.3% from 32.2%, which the company describes as keeping gross profitability stable despite continued cost pressures. However, the margin is still well below the 35.9% of Q1 FY 2024-25. Most of that ground was lost last year, when cost of goods sold grew 26.2% against revenue growth of 19.5%.
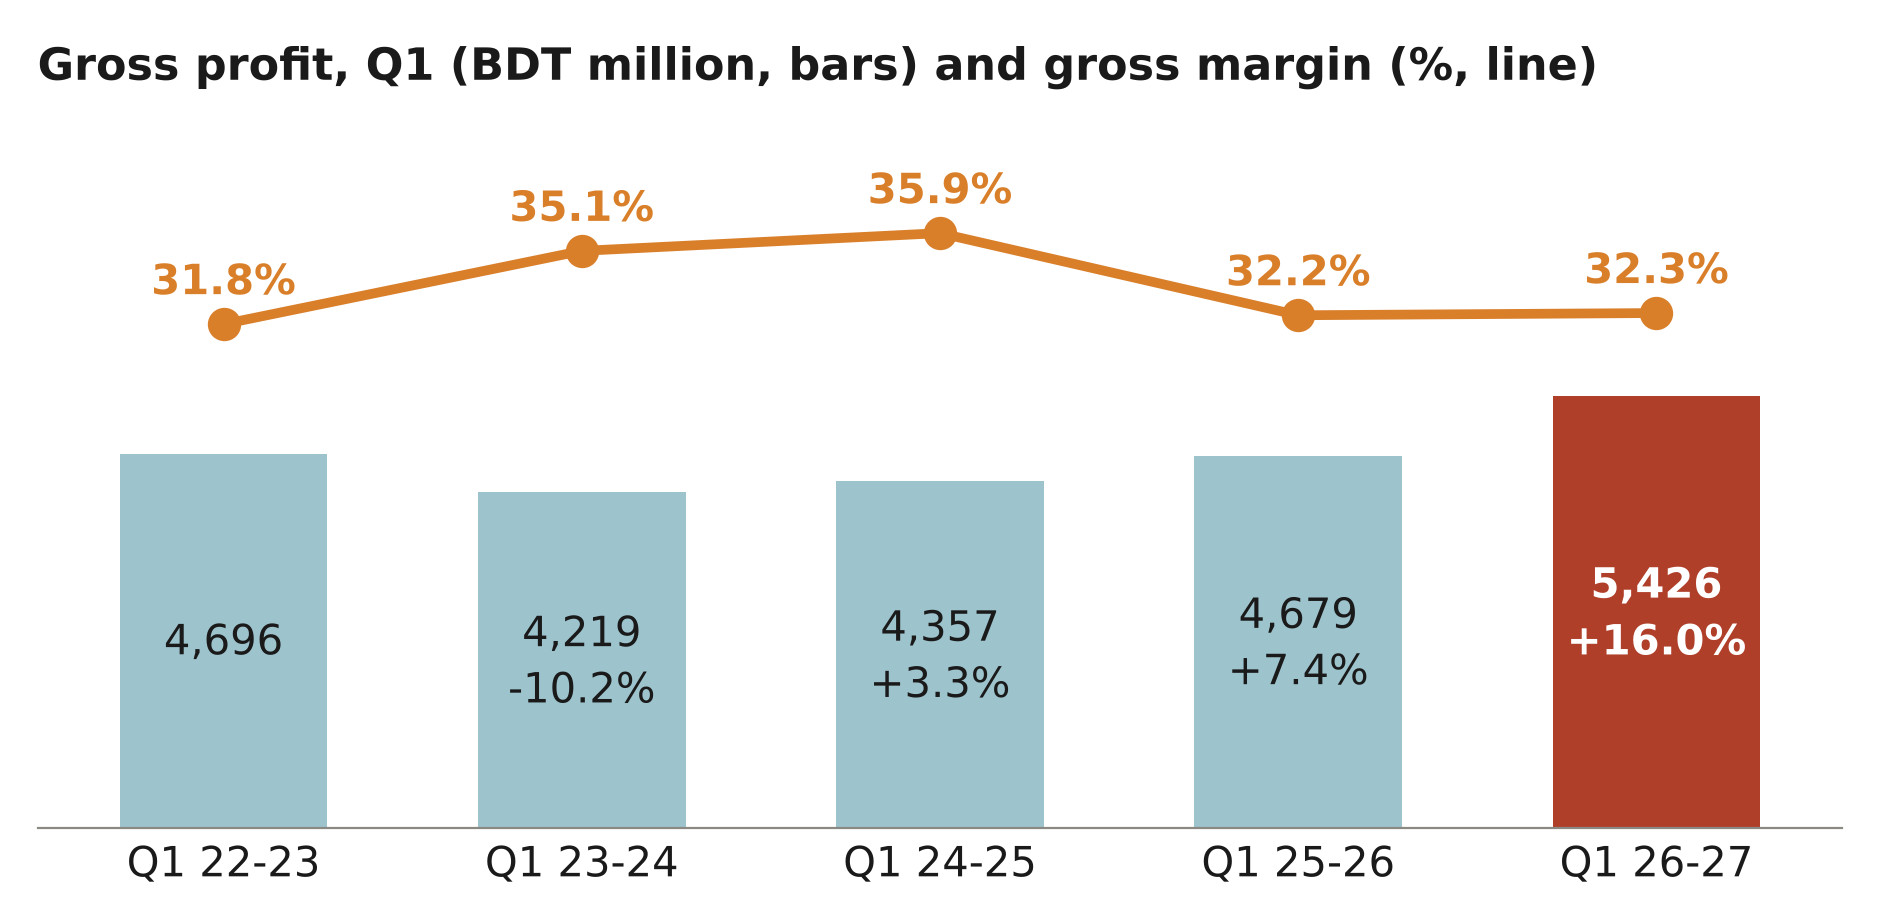
Source: Q1 quarterly reports. Gross margin = gross profit / revenue.
Higher Operating Expenses pushed NPAT to lower growth
Operating profit grew only 0.9% to BDT 2,632.2 million, and the operating margin fell to 15.7% from 18.0%, the lowest Q1 margin in five years. Operating expenses rose 34.9% to BDT 2,794.1 million, more than twice the pace of revenue, taking them to 16.6% of revenue from 14.3%. Selling and distribution expenses grew 30.2% to BDT 2,219.4 million, while administrative expenses jumped 56.8% to BDT 574.7 million. Together, the BDT 722.9 million rise in operating expenses wiped out 96.7% of the BDT 747.2 million gain in gross profit.
Net finance costs more than halved, down 51.7% to BDT 183.9 million from BDT 381.2 million. Finance costs fell 24.2% to BDT 314.4 million, while finance income nearly quadrupled to BDT 130.5 million from BDT 33.5 million. Non-operating income, however, fell 86.2% to BDT 13.3 million from BDT 96.1 million. As a result, profit before WPPF and tax grew 6.0% to BDT 2,461.5 million. After a WPPF contribution of BDT 117.2 million, profit before tax stood at BDT 2,344.3 million.
Tax expense jumped to BDT 96.9 million from just BDT 3.1 million. Current tax rose to BDT 65.6 million, as tax on interest income from fixed deposits went up to BDT 32.6 million from BDT 8.4 million and the company booked a BDT 31.2 million tax demand for income year 2022-23. A deferred tax expense of BDT 31.3 million, against an income of BDT 12.0 million last year, added to the charge. The effective tax rate rose to 4.1% from 0.1%.
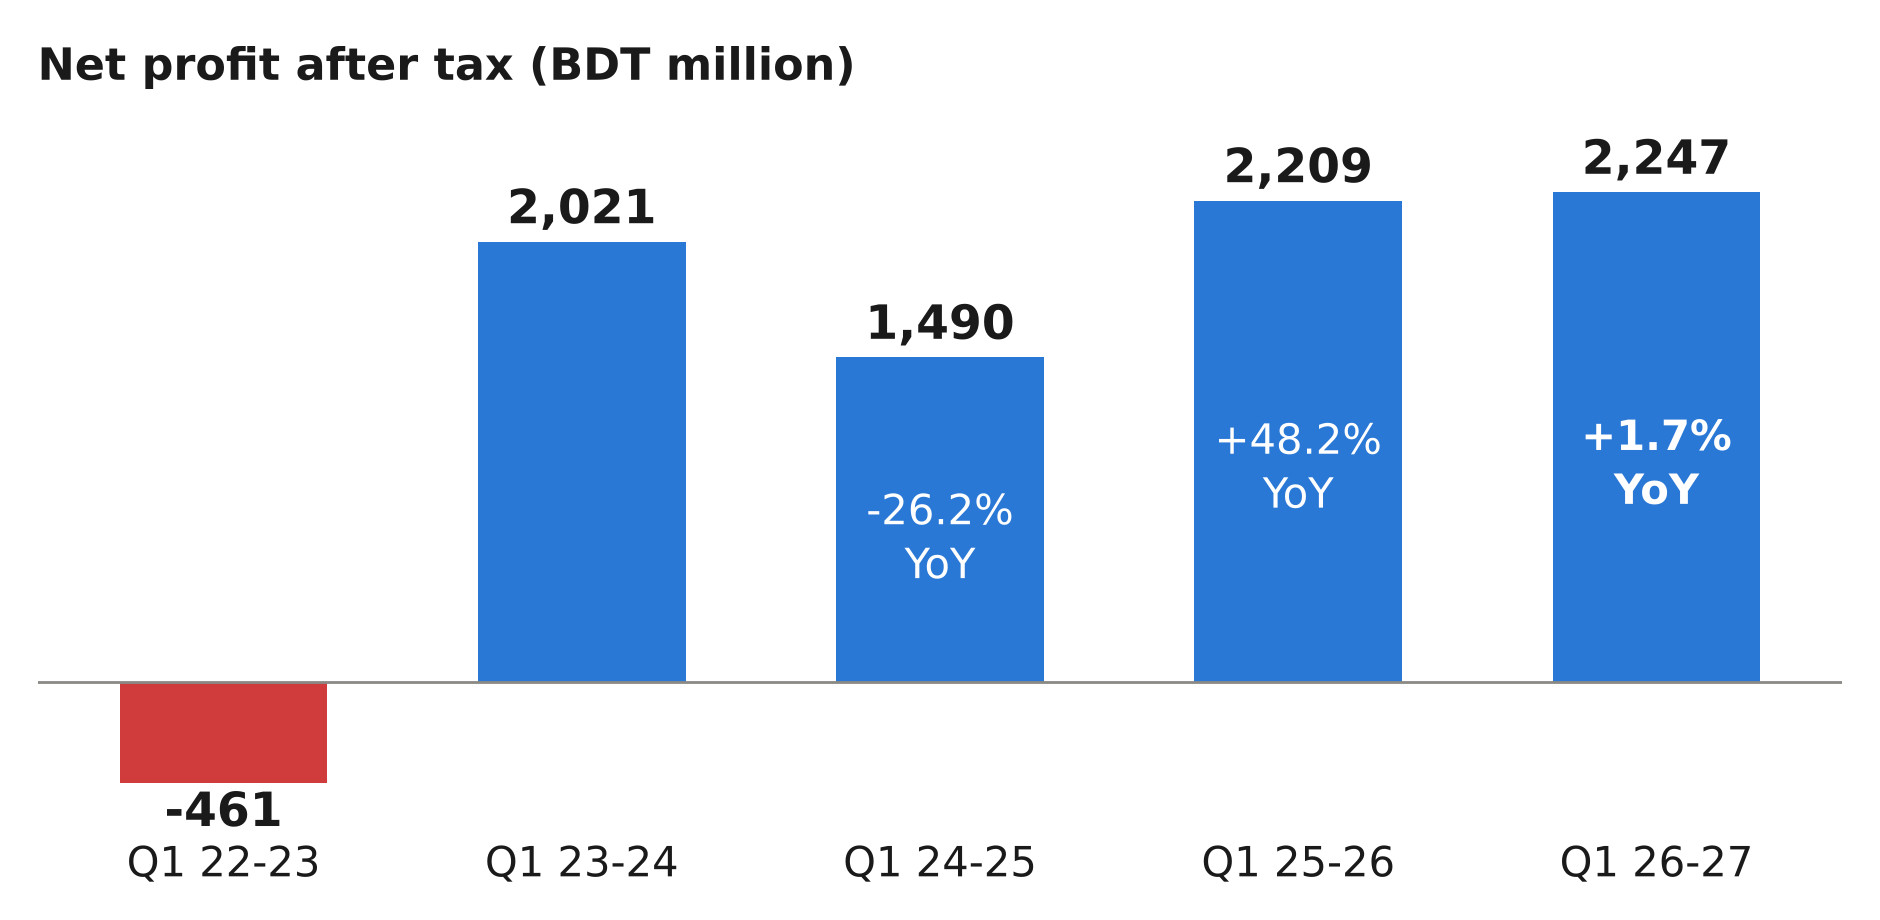
Net profit came in at BDT 2,247.4 million, the highest Q1 profit in the five years compared, but the net margin fell to 13.4% from 15.2%. Net operating cash flow per share dropped to BDT 3.53 from BDT 13.45, which the company links to a sharp rise in payments to suppliers.
Source: Q1 quarterly reports.


Leave a comment