








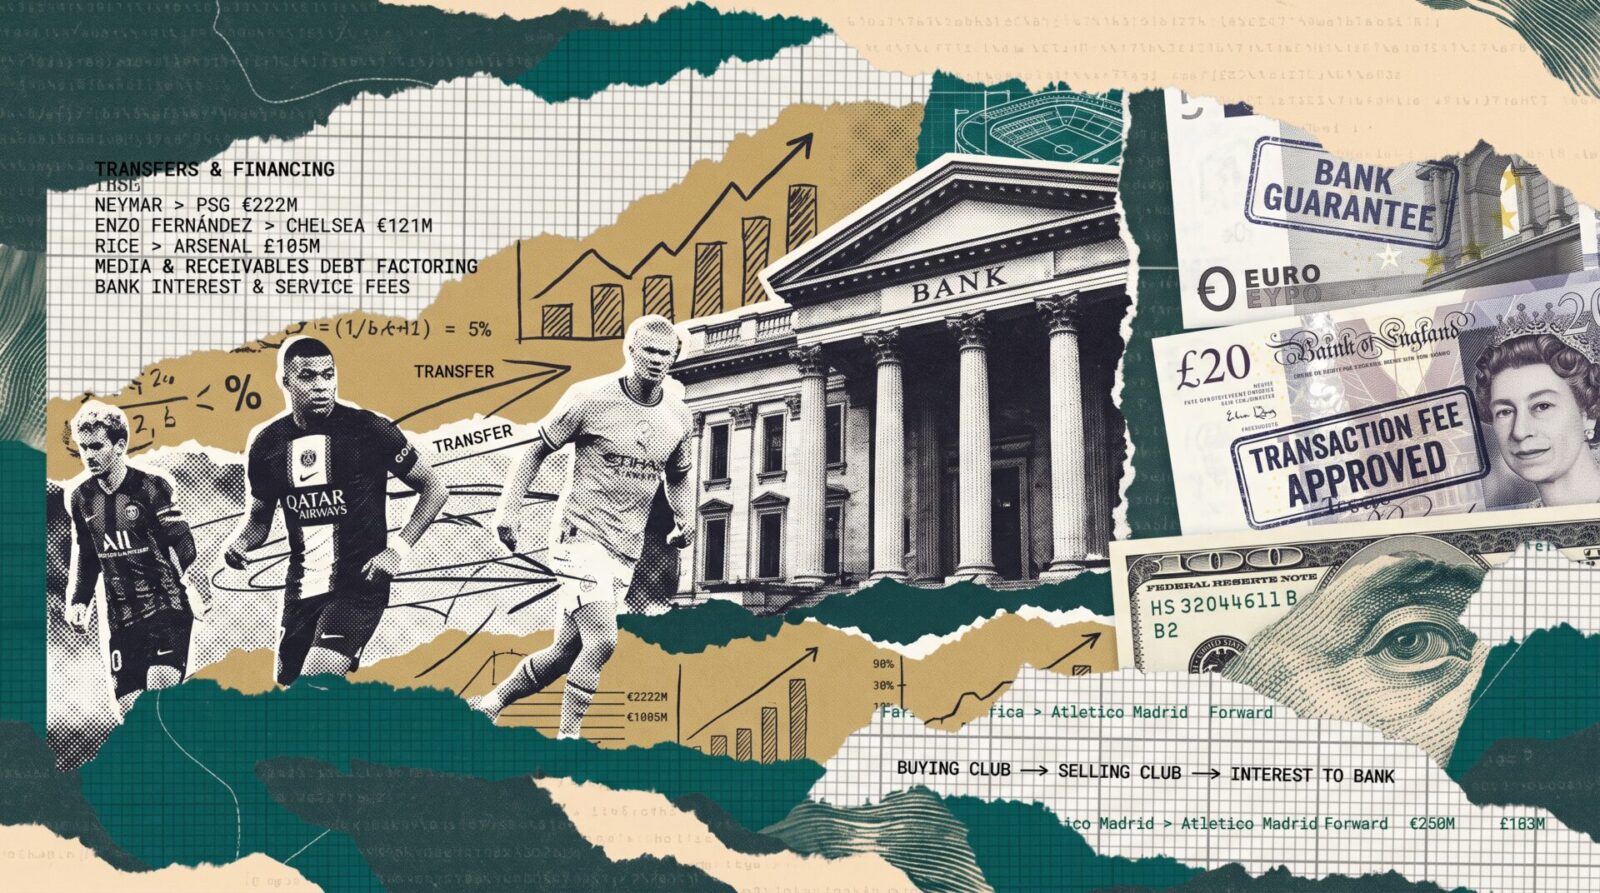
In the summer of 2026, spending in the football transfer market hit historic levels once again. Premier League clubs alone spent a record £3.49 billion (around $4.75 billion) on new player transfers in a single transfer window. On a global scale, total player transfer spending reaches well over $10 billion to $13 billion each year according to FIFA reports. Behind these headlines and player announcements, massive sums of money move between clubs across the world every day. However, the way clubs pay for these multi-million dollar transfers is rarely as simple as sending a single cash transfer.
When a club buys a player for $100 million, it almost never pays the full amount upfront in cash. Instead, clubs negotiate deferred payment structures, splitting the transfer fee into equal installments over three to five years. For example, a club might pay $20 million every year for five years. While this installment system helps the buying club manage its budget without running out of cash, it creates an immediate problem for the selling club. The selling club loses its star player today, but receives the money very slowly over time. If the selling club needs immediate cash to buy a replacement player or upgrade facilities, it faces a liquidity problem. It holds a valuable legal promise to receive money in the future, but lacks cash in hand right now. This cash flow gap is the exact problem financial institutions come in to solve.
To solve this gap, banks and financial firms use a mechanism called transfer receivables financing, or factoring. The selling club approaches a bank like Macquarie Bank or Santander and sells its legal right to collect future transfer payments from the buying club. The bank pays the selling club a lump sum of cash right away, but at a discount—for instance, giving the club $88 million upfront instead of the full $100 million spread over five years. The bank then takes over the transfer contract and directs the buying club to make all future installment payments directly into the bank’s account.
Banks generate profit from these transactions in three primary ways:
The Discount Rate (Interest Spread): The main profit comes from the difference between the discounted cash paid to the seller upfront ($88 million) and the total installments collected from the buyer over time ($100 million). This difference acts as the bank’s return for advancing the capital.
Arrangement and Structuring Fees: Banks charge upfront administrative fees, typically between 1% and 2.5%, for legal structuring, international compliance, and evaluating credit risk.
Foreign Exchange (FX) Spreads: Transfers between international leagues often involve multiple currencies, such as Euros and British Pounds. Banks charge spread fees when converting these currency payments over the life of the loan.
Banks view transfer receivables as an attractive product because default rates are extremely low. Football governing bodies like FIFA and UEFA enforce strict “football creditor rules,” meaning clubs face severe penalties—including points deductions and transfer bans—if they fail to pay transfer debts on time.
In conclusion, transfer receivables financing serves as essential financial plumbing for the global sports industry. Selling clubs gain immediate cash to reinvest in new players, buying clubs gain flexible payment schedules, and banks secure consistent, low-risk profits. By turning long-term promises into instant cash, banks keep the global football transfer market moving smoothly season after season.
For more updates, be with Markedium.



Leave a comment