







BRAC Bank PLC, one of Bangladesh’s largest private commercial banks, reported a standalone net profit of BDT 15,838.1 million for the first nine months (9M) of 2026, marking a 50.1% year-on-year increase from BDT 10,552.0 million in the same period of 2025. The robust earnings growth was primarily driven by a sharp rise in investment income, particularly from government securities, along with a rebound in net interest income.
Loan Book Grows 6.7% Since December to BDT 779,468.7 Million
BRAC Bank’s loans and advances stood at BDT 779,468.7 million as at 30 September 2026, up 6.7% from BDT 730,658.8 million at the end of December 2025, adding BDT 48,809.9 million in nine months. Compared with September 2025, the loan book was up 15.4%. On a year-end basis, loans grew 26.5% in 2023, 20.0% in 2024 and 17.2% in 2025, indicating a gradual moderation in credit growth, though the bank added more than BDT 100,000 million to its loan book in each of those three years.
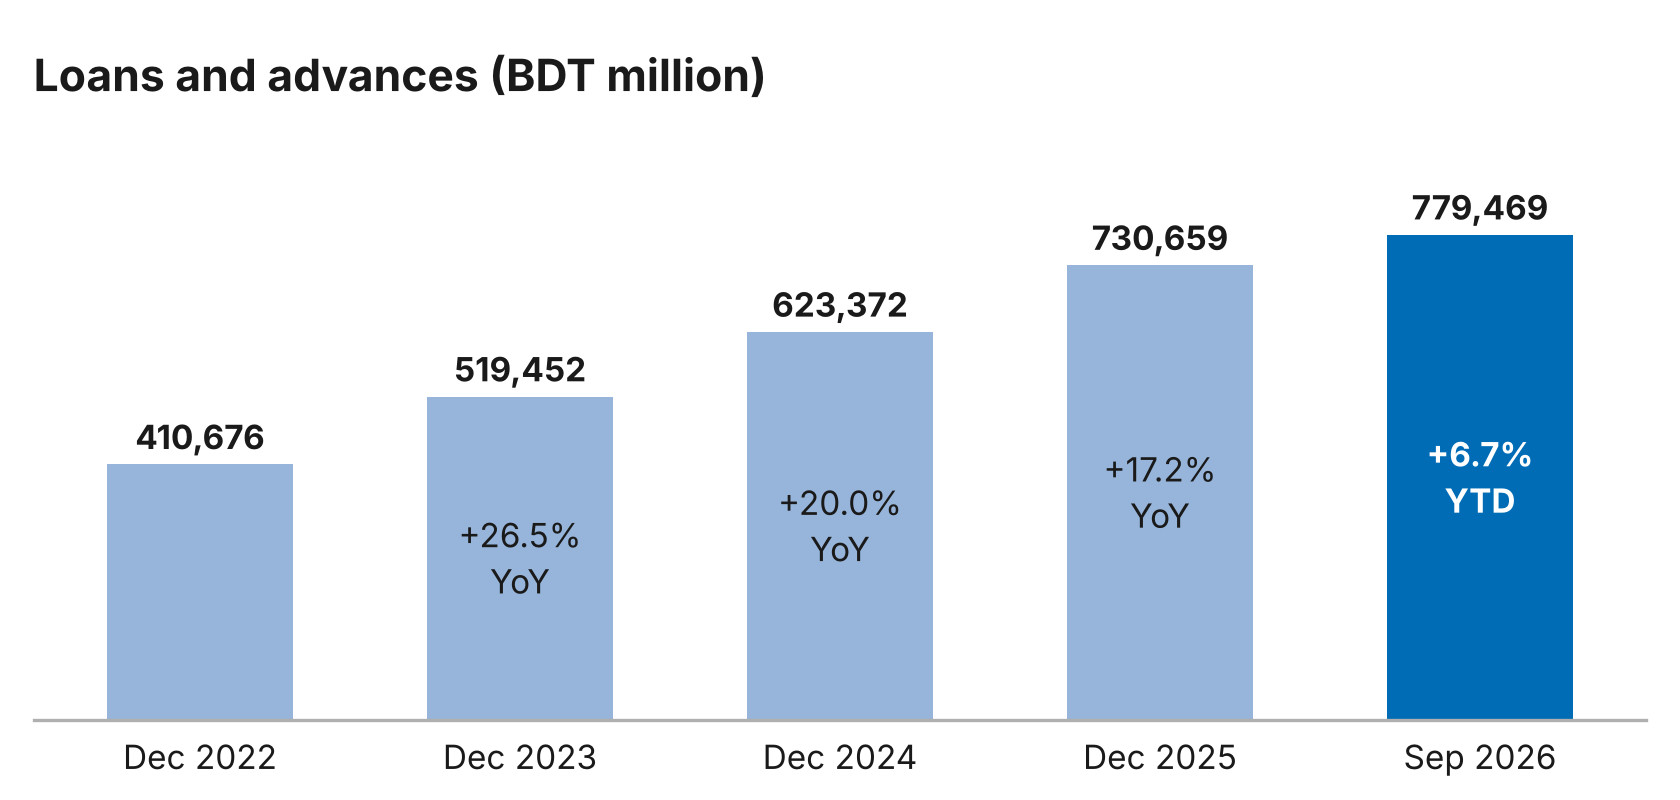
Source: BRAC Bank PLC standalone financial statements. Year-end balances as at 31 December and latest as at 30 September 2026, in BDT million; Sep 2026 growth is against Dec 2025 (YTD).
NPL Ratio Holds at 2.27% as Bad/Loss Loans Fall 34.5%
BRAC Bank’s total non-performing loans (NPLs), comprising sub-standard, doubtful and bad/loss loans, stood at BDT 17,697.1 million as at 30 September 2026, up 6.8% from BDT 16,568.9 million at the end of December 2025. As the loan book expanded at a similar pace, the NPL ratio remained unchanged at 2.27%. On a year-end basis, the ratio has improved steadily from 3.72% in December 2022 to 3.38% in December 2023, 2.63% in December 2024 and 2.27% in December 2025.
Classification | Dec 2022 | Dec 2023 | Dec 2024 | Dec 2025 | Sep 2026 | YTD Growth |
|---|---|---|---|---|---|---|
Sub-standard | 3,376.2 | 2,474.6 | 2,288.1 | 2,831.9 | 6,987.8 | 146.8% |
Doubtful | 2,535.9 | 2,204.9 | 737.4 | 2,609.4 | 3,415.3 | 30.9% |
Bad/Loss | 9,356.4 | 12,854.4 | 13,377.8 | 11,127.7 | 7,294.0 | -34.5% |
Total NPL | 15,268.6 | 17,533.9 | 16,403.3 | 16,568.9 | 17,697.1 | 6.8% |
NPL ratio | 3.72% | 3.38% | 2.63% | 2.27% | 2.27% | – |
Source: BRAC Bank PLC standalone financial statements. Year-end balances as at 31 December and latest as at 30 September 2026, in BDT million. YTD
growth = Sep 2026 vs Dec 2025
The composition of NPLs shifted notably during the period. Bad/loss loans dropped 34.5% to BDT 7,294.0 million from December 2025, after a 16.8% decline during 2025, reducing their share of total NPLs to 41.2% from 67.2% at the end of 2025 and 81.6% at the end of 2024. Recovery from previously written-off loans also rose 62.4% to BDT 1,162.7 million in 9M 2026.
However, the early-stage categories point to fresh stress. Sub-standard loans more than doubled (up 146.8%) to BDT 6,987.8 million since December 2025, after rising 23.8% in 2025, while doubtful loans increased 30.9% to BDT 3,415.3 million. Together, these two categories now account for 58.8% of total NPLs, up from 32.8% at the end of 2025. The bank’s NPL coverage ratio, including general provision, stood at 134%.
Deposits Cross the BDT 1 Trillion Mark
BRAC Bank’s deposits rose 15.9% to BDT 1,030,910.2 million as at 30 September 2026 from BDT 889,517.4 million at the end of December 2025, crossing the BDT 1 trillion mark. Compared with September 2025, deposits were up 22.8%. On a year-end basis, deposits grew 33.7% in 2023, 34.0% in 2024 and 29.2% in 2025, consistently outpacing loan growth.
Since December 2025, savings deposits recorded the fastest growth among the major categories, rising 31.0% to BDT 169,992.6 million, followed by term deposits at 14.6% (BDT 585,518.1 million) and current and other accounts at 10.9% (BDT 261,954.7 million). Low-cost current and savings deposits (CASA) made up 41.9% of total deposits, up from 41.1% at the end of 2025, while term deposits remained the largest funding source at 56.8%. With deposits growing faster than loans, the gross loan-to-deposit ratio eased to 75.6% from 82.1% in December 2025.
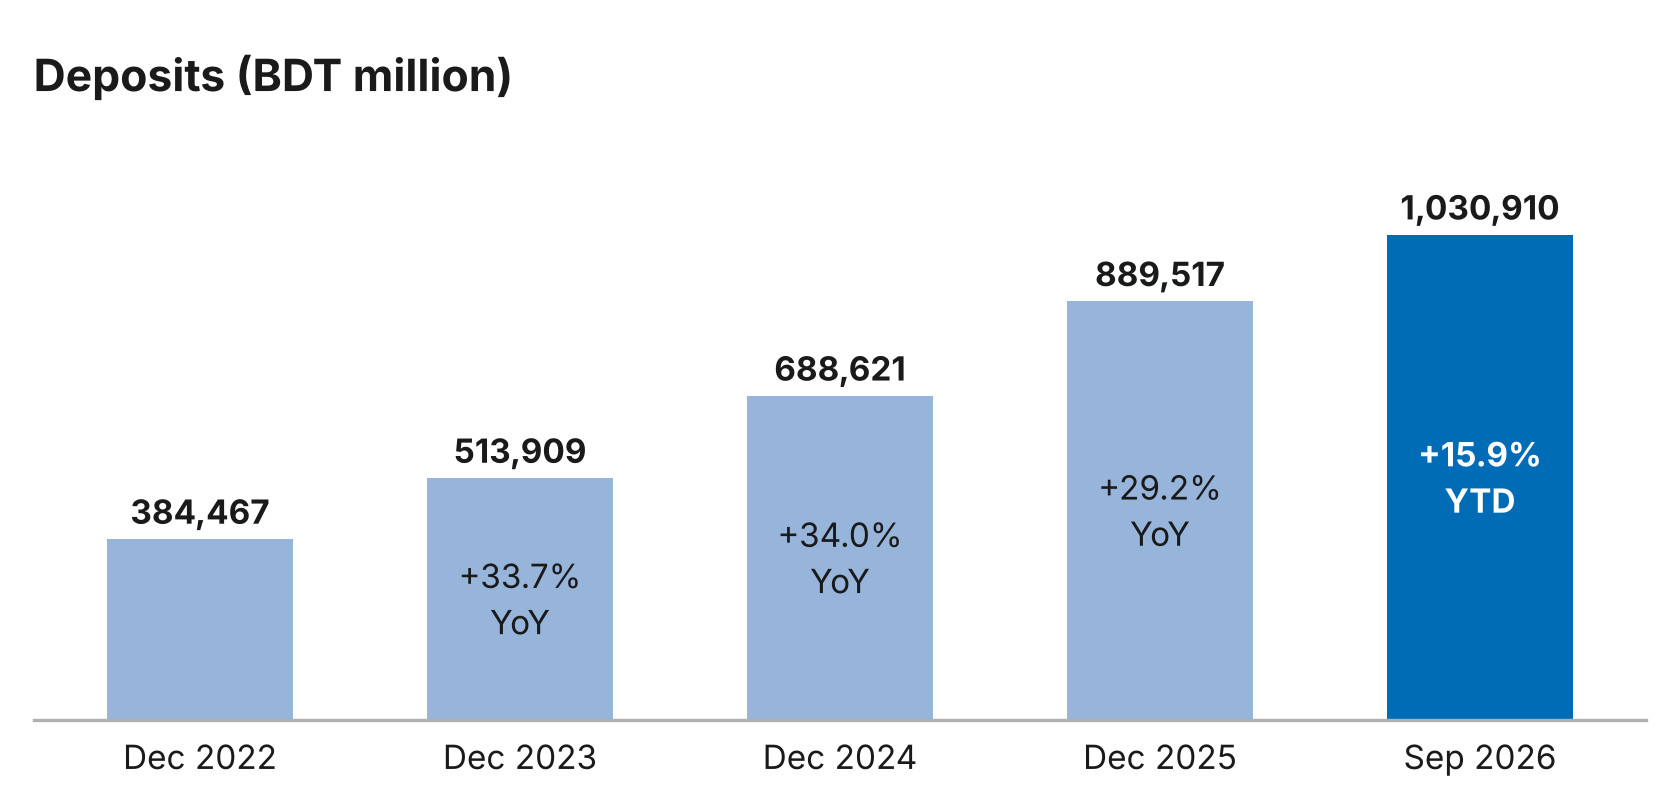
Source: BRAC Bank PLC standalone financial statements. Year-end balances as at 31 December and latest as at 30 September 2026, in BDT million; Sep 2026 growth is against Dec 2025 (YTD).
Net Interest Income Rebounds 28.2%
Net interest income (NII) grew 28.2% year-on-year to BDT 11,304.9 million in 9M 2026, reversing two consecutive years of decline (down 21.2% in 9M 2024 and 14.5% in 9M 2025). Interest income rose 18.5% to BDT 64,473.3 million, led by a 20.1% increase in interest on loans and advances to BDT 64,158.1 million, while interest expenses rose at a slower 16.7% to BDT 53,168.4 million. Interest paid on deposits climbed 20.0% to BDT 42,866.5 million, broadly in line with deposit growth, but interest on borrowings increased only 9.6%. The bank’s cost of fund declined to 6.50% from 6.95% in December 2025.
Investment income remained the bank’s largest earnings source, rising 31.9% to BDT 34,663.2 million and accounting for 65.2% of total operating income. Interest on government securities surged 42.2% to BDT 31,562.1 million, making up 91.1% of investment income, up from 84.4% a year earlier, as the bank’s holdings of government securities grew to BDT 411,040.9 million from BDT 313,828.8 million in December 2025. In contrast, capital gains on government securities fell 32.7% to BDT 2,228.5 million and interest on corporate and subordinated bonds declined 14.8% to BDT 224.2 million, while dividend income from shares and mutual funds rose 31.9% to BDT 588.3 million.
As a result, total operating income increased by BDT 12,021.6 million, or 29.2%, to BDT 53,166.3 million. Investment income contributed 69.7% of this increase, NII 20.7% and commission, exchange and brokerage income, which rose 19.5% to BDT 6,961.4 million, 9.4%.
Salaries Drive a 14.2% Rise in Operating Expenses
Operating expenses rose 14.2% to BDT 21,813.2 million, an increase of BDT 2,711.7 million. Salaries and allowances were the main driver, rising 16.3% to BDT 12,681.5 million and accounting for 65.4% of the total increase. Other expenses grew 10.1% to BDT 4,392.8 million and depreciation and repairs of bank assets rose 12.9% to BDT 2,929.5 million, together contributing a further 27.2% of the increase. With income growing about twice as fast as costs, the cost-to-income ratio improved to 41.0% from 46.4%, and profit before provisions jumped 42.2% to BDT 31,353.1 million.
Provisions Edge Up 6.0% as Net Profit Jumps 50.1%
Total provisions rose 6.0% to BDT 5,233.8 million. Specific provision for loans and advances increased 39.7% to BDT 5,846.5 million, but this was largely offset by higher recoveries from written-off loans and a sharp fall in general provision to BDT 404.1 million from BDT 1,443.8 million. Net loan loss provision therefore rose only 3.5% to BDT 5,087.9 million. The bank also set aside BDT 345.5 million for off-balance sheet items, compared with none a year earlier, and wrote back BDT 215.0 million on investments.
Profit before tax grew 52.7% to BDT 26,119.2 million. After a 56.9% rise in tax provision to BDT 10,281.1 million, net profit increased 50.1% to BDT 15,838.1 million.
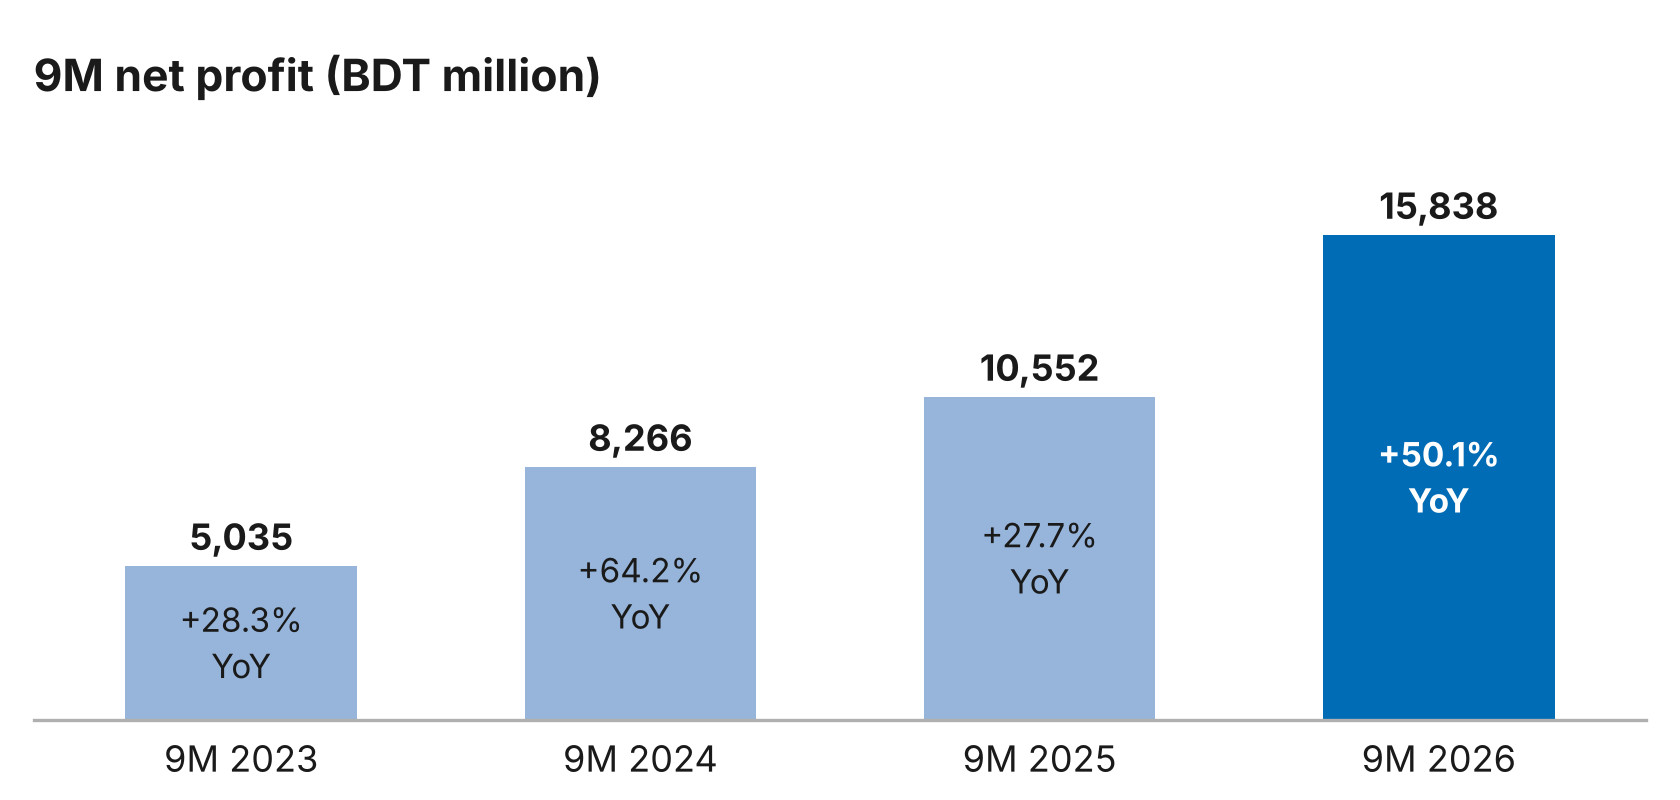
This is the bank’s highest nine-month profit in the four-year review period, with net profit growing at a compound annual rate of 46.5% since 9M 2023.
Q3 Net Profit Rises 26.6%
In the third quarter (July–September 2026) alone, total operating income rose 26.3% year-on-year to BDT 19,427.1 million. NII climbed 71.6% to BDT 4,172.6 million and investment income increased 16.2% to BDT 12,719.0 million. Operating expenses grew 11.7%, lifting profit before provisions by 38.0% to BDT 11,787.3 million. However, provisions surged 78.9% to BDT 2,606.6 million, which moderated bottom-line growth. Net profit for the quarter rose 26.6% to BDT 5,506.0 million from BDT 4,349.7 million, contributing 34.8% of the bank’s nine-month profit.
On a consolidated basis, BRAC Bank PLC and its subsidiaries reported a net profit of BDT 21,209.5 million in 9M 2026, up 38.1% from BDT 15,358.6 million in 9M 2025.


Leave a comment